Thursday, August 24, 2006
College Application Process
Even though I'm still quite young, the whole applying to college activity already gets me stressed (I think it's time for my nap) I'm happy that I won't have to worry about financing on top of that. usatoday has a "real life" article on the admission process that's worth a read for anyone who will be going through it soon.
Monday, August 21, 2006
Free College Textbooks For Viewing Ads
My uncle has been talking to me about the rising cost of textbooks and how they can cost close to $1000 a year now. While buying them second hand can help save some money, my little head started to think, "wouldn't it be great if there was an easy way to be able to get college textbooks for free?" I babbled this to my uncle (still working on this talking thing and see it as highly over-rated when I get all these smiles when I babble) and he said he'd look into it to see if there was anything like that. Today he came back with a answer...
There is a new website called Freeload Press that offers college textbooks for free download in e-book form in exchange for advertising. Students (or even little babies like me if I could get the computer key thing down) can take a 5 minute survey and then download a PDF file of the textbook which can be stored on a computer and printed out if need be. The ebook textbook may also display ads to help pay for offering it for free.
The site is still small, but they are hoping to have 250,000 free textbooks in their inventory by next year. It sounds like a good idea to me. That would mean $1000 a year less out of my pocket that I can save for other things and even at this early age, that is a great deal in my opinion...
There is a new website called Freeload Press that offers college textbooks for free download in e-book form in exchange for advertising. Students (or even little babies like me if I could get the computer key thing down) can take a 5 minute survey and then download a PDF file of the textbook which can be stored on a computer and printed out if need be. The ebook textbook may also display ads to help pay for offering it for free.
The site is still small, but they are hoping to have 250,000 free textbooks in their inventory by next year. It sounds like a good idea to me. That would mean $1000 a year less out of my pocket that I can save for other things and even at this early age, that is a great deal in my opinion...
Tuesday, August 15, 2006
Financial Aid - How To Pay For College
As my uncle reads to me more about college and finances, I'm coming to understand that many parents and kids have not saved money well in advance as I am. I hope that this blog will encourage more people to do so even if it only means putting aside a few dollars a week at an early age.
For those that haven't saved enough for college, Fox News has an article up called The Financial Aid Game: How to Pay For College which gives a solid five step process with links to quality information. The five steps are:
Know the Lingo
Don't Be Scared by the Price Tag — Apply
There's Money Out There — Go Find It!
You Can Do It Cheaper
Make the Grade, and Don't Give Up
This is worth a quick read if you are looking for ways to increase your financial aid package for college.
For those that haven't saved enough for college, Fox News has an article up called The Financial Aid Game: How to Pay For College which gives a solid five step process with links to quality information. The five steps are:
This is worth a quick read if you are looking for ways to increase your financial aid package for college.
Saturday, August 05, 2006
Beware Of College Aid Loan Preferred Lists
I'm now walking pretty darn well, but I still don't have the reading thing down. That's okay because my uncle takes the time to do some reading for me. Here is an interesting article by John Wasik from Bloomberg News regarding the preferred lender lists that colleges give to those new students searching for loans that he read me about:
The article goes on to say that rates may be better outside the preferred list and it's worthwhile checking other local lending institutions besides the college-aid loan list. Something for all of you looking at college loans to consider...
When students or parents approach a college financial-aid office for a federal loan, they may not be getting the best possible deal.
Borrowers are often given a ``preferred list'' of lenders certified by the college. You may believe that these are the best loans available since they are chosen by the aid office.
Getting a loan outside of the preferred list may even be discouraged by the college, which is heavily marketed by lenders.
The article goes on to say that rates may be better outside the preferred list and it's worthwhile checking other local lending institutions besides the college-aid loan list. Something for all of you looking at college loans to consider...
Tuesday, August 01, 2006
Student Aid and Assets
One of the big positives of me getting my college finances in order at an early age is that I hopefully won't need to worry about college aid and that entire aid process. Unfortunately, there are a lot of people who didn't start saving early so they will need to get college financing aid. One of the ways that families try to maximize the aid for the student going to college is to shift assets so they aren't counted toward the financial aid formula. There is nothing wrong with this and moving assets can make a significant difference in the amount of aid that may be available, but you need to be careful not to go overboard when doing this as this article indicates:
The article goes on to give quality advice on how to move the assets which even my uncle would endorse as a good personal finance move. Cash and other investments are counted in the formula which can reduce the amount of financial aid available. If you take the cash or sell the assets to pay down credit card debt or mortgage debt, they will no longer be counted in the formula.
Of course, the best strategy is to start saving early so that the financial aid isn't a necessity in the first place, but it is worthwhile learning more about how to leverage the system to your advantage if you're in the position of needing financial aid.
But sorting out the best moves is not easy: In general, there are no hard and fast rules. And while there is nothing wrong with rearranging your finances to increase the chances of getting aid, parents who try too hard to game the system risk being charged with a crime.
“I have seen people lie about assets that they have,” said Ray Loewe, founder of College Money, a New Jersey advisory firm that specializes in college finances. “Basically, if you have an asset and you don’t disclose it, it’s fraud.”
The article goes on to give quality advice on how to move the assets which even my uncle would endorse as a good personal finance move. Cash and other investments are counted in the formula which can reduce the amount of financial aid available. If you take the cash or sell the assets to pay down credit card debt or mortgage debt, they will no longer be counted in the formula.
Of course, the best strategy is to start saving early so that the financial aid isn't a necessity in the first place, but it is worthwhile learning more about how to leverage the system to your advantage if you're in the position of needing financial aid.
Monday, July 31, 2006
Teaching Personal Finance At School
I came across a piece that says that teachers in Pennsylvania are going to school to learn to teach personal finance. Even at a year, I think this is an excellent approach to take. Even though I still believe that it is ultimately the parents' responsibility, basic personal finance education is still a good thing:
Let's hope that this is something that is encouraged in every state in the coming years.
"Many young people today lack the basic knowledge needed to understand the increasingly complex financial marketplace - building credit, understanding interest rates and planning for retirement," said Banking Secretary Bill Schenck. "The average score among high school students in a recent survey on financial literacy was a little over 50 percent. This shows an important need to educate students in personal finance."
Let's hope that this is something that is encouraged in every state in the coming years.
My First Wedding
Mom and dad took me to me to my first wedding this weekend and I got to dress up in a fancy blue dress for the event. Weddings are a lot of fun because there are flower petals on the ground that you can pick-up and play with. Even though this wasn't my event (I think I'll hold off until after college to start considering that), I must say that after the bride, I was the most popular guest there (^_^)


Sunday, July 30, 2006
Reallionaire
If kids are given the chance and taught, they can go a long way to get their finances in order at an early age. The Reallionaire is one of those examples:
I especially found his "five person policy" to be a great idea. When looking for help with his projects, when a person said "no" and wouldn't help him, he didn't leave it like that. Instead, he asked the person not willing to help to give him the names of 5 people that might be willing to help. Easy and brilliant.
Parents give their kids all kinds of extra curricular activities. It may be a musical instrument, joining a sports team, clubs like boy scouts or girl scouts, swimming lessons, etc. Why don't they give them money / entrepreneurial lessons too?
(hat tip: Thrifty Ray)
Farrah Gray began contributing to his family's financial support at the age of 6, and he made his first million by the time he was 14. His success made a lot of people change their thinking about where life in the projects of Chicago's South Side could lead.
I especially found his "five person policy" to be a great idea. When looking for help with his projects, when a person said "no" and wouldn't help him, he didn't leave it like that. Instead, he asked the person not willing to help to give him the names of 5 people that might be willing to help. Easy and brilliant.
Parents give their kids all kinds of extra curricular activities. It may be a musical instrument, joining a sports team, clubs like boy scouts or girl scouts, swimming lessons, etc. Why don't they give them money / entrepreneurial lessons too?
(hat tip: Thrifty Ray)
Saturday, July 15, 2006
The Cost Of College Textbooks
When thinking about college expenses, most of the time I think about tuition and housing costs, but the cost of textbooks is another aspect I need to consider when planning my finances for college. Some facts on the cost of college text books from an article I came across:
Since I still have 17 years before I will be attending college, books are likely to be a lot more expensive then. I'll have to keep on top of ways that I can reduce the costs of textbooks. Here are a few from the article:
Use free sites such as campusbookswap.com where students are able to buy and sell used books directly from one another.
Consider purchasing textbooks online from used and discount textbook sellers, but remember to calculate shipping into their costs.
Before purchasing a textbook, be sure to check the ISBN number to make sure you're purchasing the correct book. Also, makes sure it's the correct edition.
Contact the professor to see if an older edition of the textbook is acceptable. Older editions will be a fraction of the cost.
Used textbooks are much cheaper than new books - typically 75% less than new college textbooks.
Find the which textbooks you need to purchase even before you head back to school. Many college bookstores post the required textbooks online for each course. If you wait until you return, any used textbooks (and their cheaper prices) will be long gone.
A Government Accountability Office report found that in the past two decades, college textbook prices have increased at twice the rate of inflation. In academic year 2003-04, students and their families spent more than $6 billion on new and used textbooks.
According to the GAO, the average estimated cost of books and supplies for a first-time, full-time student in 2003-04 was $898 at four-year public institutions. That amounted to about 26 percent of the cost of tuition and fees.
At two-year public institutions, where low-income students are more likely to pursue a degree program and tuition and fees are lower, the average estimated cost of books and supplies per first-time full-time student was $886, representing almost three-quarters of the cost of tuition and fees, according to the GAO report.
That, folks, is not chump change when you consider that so many students are already heavily borrowing to attend college. It's not unusual for one textbook to cost more than $100.
Since I still have 17 years before I will be attending college, books are likely to be a lot more expensive then. I'll have to keep on top of ways that I can reduce the costs of textbooks. Here are a few from the article:
Thursday, July 13, 2006
Birthday Savings
For my first birthday, I got a lot of clothes and other gifts from friends and family. I also got to increase my college savings by an extra $100 as a gift from my uncle. He sat down and told me that he wouldn't be getting me gifts for my birthday, Christmas or other special events, but will always add a little bit to my college fund instead. Since I get a lot of great gifts from everyone else, I think this is a good strategy and will help make sure that the college fund is being looked after.
I have been catching up on getting all my financial numbers in order. While I'm not quite done yet, I did learn that this site is now generating over $150 a month in income for me. If I can keep that pace for the next 17 years without any other income or interest, that will give me over $30,000 for my college fund. It goes to show how saving over a long period can add up to quite a bit, especially if you begin early.


I have been catching up on getting all my financial numbers in order. While I'm not quite done yet, I did learn that this site is now generating over $150 a month in income for me. If I can keep that pace for the next 17 years without any other income or interest, that will give me over $30,000 for my college fund. It goes to show how saving over a long period can add up to quite a bit, especially if you begin early.
Tuesday, July 11, 2006
Let Me Eat Cake!
The best part of any birthday party is getting to eat birthday cake! As you can see in the photos below, I had a great time digging into my birthday cake and must say I did a pretty good job of eating it on my own. I had even a better time eating it than keeping track of my finances (don't tell my uncle) so I'm showing this part of the day before going into the financial part of it. Wish you could have been there to eat cake with me (^_^)


Thursday, July 06, 2006
Happy Birthday To Me!!
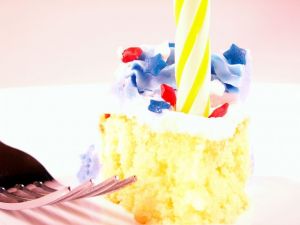
Happy Birthday to me
Happy Birthday to me
Happy Birthday dear Margot
Happy Birthday to me
That's right, I've spent my first year on this earth. I'm no longer counting months and now can proudly say I'm a full year old. No more fractions. A full, round number.
The best is to come this weekend when I'll have my birthday party with all kinds of friends and family. The plan is to have the birthday party in the park with BBQ and lots of cake (mom has been feeding me these organic cheerios with no sugar which I know are good for me, but you can bet I'll be diving into that cake!)I'll be sure to get lots of photos taken to share them with all of you.
Now to get my first year financial totals in order to share...
Wednesday, July 05, 2006
If You Have The Will...
Here is a wonderful story I came across that shows that if you want to go to college (or in this case, send your daughter to college) if you have the will and determination, there is a way to achieve it. While I'm planning ahead so that this won't be an issue when it's time for me to go to college (and encourage all of you to do the same), it's another example of how creativity and good old hard work can go a long way to get you where you want to go:
It didn't stop there. The inspiration that the effort they put in to making sure her daughter went to college inspired others and it has now been turned into a non profit organization to help others wanting to attend college. It's a wonderful story that shows the possibilities when you are committed.
It sure shows that putting away a bit of money now isn't near as difficult as many might make it out to be. I am happy that my parents chose my uncle to help out in this area - wouldn't it be nice if every adult would put the same effort toward a child to improve their future?
Her daughter, Shewanda Dawn Russell, a 1991 graduate of Monessen High School, earned a scholarship to attend Spring Garden College in Philadelphia to study architecture, but was devastated when the school closed.
Her daughter not only lost her scholarship but her credits as well, and Russell says to this day they still don't know what happened.
A single mother, Cherie Russell welcomed her daughter back home, but contemplated how she could afford to send her to another college.
So she recruited some friends, Ida Allums, Chris Jordan and Mary Hall, all of Monessen, to help her set up fundraisers. They sold everything "you could imagine" to send her daughter to Tuskegee University...
It didn't stop there. The inspiration that the effort they put in to making sure her daughter went to college inspired others and it has now been turned into a non profit organization to help others wanting to attend college. It's a wonderful story that shows the possibilities when you are committed.
It sure shows that putting away a bit of money now isn't near as difficult as many might make it out to be. I am happy that my parents chose my uncle to help out in this area - wouldn't it be nice if every adult would put the same effort toward a child to improve their future?
Tuesday, July 04, 2006
I Love Pasta!
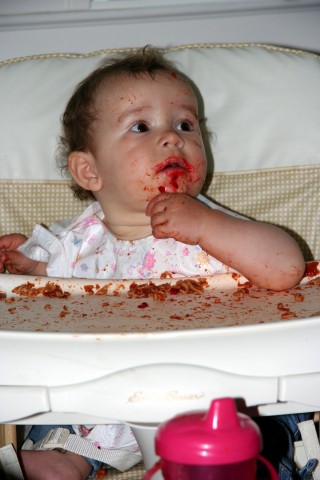 I like pasta! There is no doubt about that as you can see in this photo. While I do need some more practice in utensil use (I just don't see why everyone can't eat with their hands like me), I think I'll get the hang of it in the coming years. It's a good thing my finances won't be this messy when it's time for college.
Sunday, June 25, 2006
High School "A" Is A College "C"
I know that I don't even know how to write yet (I can't even talk, although I do a great babble!), but I still found it interesting that an "A" high school paper is a "C" college paper. Along with having my finances in order, I'll also make sure to work on my writing...
Tuesday, June 20, 2006
Consolidate Student Loans Now Or Pay A Lot
If you haven't consolidated your Federal student loans yet, time to get off your diaper (okay, most of you reading aren't still in diapers, but you know what I mean) and get it taken care of. If you have procrastinated this long, it's becasue you think its a hassle, but that hassle will save you a few thousand dollars in interest charges and maybe a lot more - your deadline for getting it done is July 1.
President Bush has also made it a bit easier for you to do so. The old law stated that you has to consolidate your federal student loans with the same entitiy where you received your original student loan and it was a pain for some to try and figure out where that was. As part of an emergency spending bill signed recently by President Bush, Federal student loans can be consolidated with any lender meaning you have one less excuse to get this taken care of right away..
From Saving Advice:
There are only a couple of weeks left, so put it on your calendar to get the process to consolidate those loans moving today.
President Bush has also made it a bit easier for you to do so. The old law stated that you has to consolidate your federal student loans with the same entitiy where you received your original student loan and it was a pain for some to try and figure out where that was. As part of an emergency spending bill signed recently by President Bush, Federal student loans can be consolidated with any lender meaning you have one less excuse to get this taken care of right away..
From Saving Advice:
For example, Stafford loans will rise to 7.1% from the current 5.375%. Borrowers who consolidate loans they're already repaying can lock in this rate if they do so before July 1. For those that happen to be in their "grace period" (the six-month window between graduation and when they're required to start making payments on their student loans), they can lock in an interest rate of 4.75%.
There are only a couple of weeks left, so put it on your calendar to get the process to consolidate those loans moving today.
Friday, June 16, 2006
Is Student Aid Really Shrinking?
I came across this little news item that says that student aid shrinking is really a myth;
Whether student aid is shrinking or increasing, a lot of that aid is in the form of student loans which need to be repaid at some point in the future. That is why I'm getting these finances in order early so that I don't have to worry about the situation in either case - I hope that many of you will join me.
According to the College Board, which reports annually on changes in student aid and college costs, aid has actually been growing – a lot! By the Board’s numbers, between the 1994-95 and 2004-05 academic years, total inflation-adjusted federal student aid more than doubled, from $44.5 billion to $90.1 billion.
And that growth wasn’t only in loans, as student advocates often complain. Real Pell Grant funding rose from $7 billion to $13.1 billion, supplemental grants increased from $743 million to $771 million, work-study rose from $965 million to $1.2 billion, and federal tax benefits increased from nothing to more than $8 billion.
In fairness, just because total federal aid grew doesn’t necessarily mean that aid per-student rose. Maybe State PIRG members and twenty-something agitators still have a legitimate point. Or maybe not: Again, according to College Board data, between 1994-95 and 2004-05 inflation-adjusted grant aid per student from both federal and other sources ballooned 51 percent, from $2,965 to $4,479, and overall aid rose 61 percent, from $6,261 to $10,119.
Moreover, both grant and overall aid increases outpaced the growth in college costs.
Whether student aid is shrinking or increasing, a lot of that aid is in the form of student loans which need to be repaid at some point in the future. That is why I'm getting these finances in order early so that I don't have to worry about the situation in either case - I hope that many of you will join me.
Meeting With My Uncle
I got to see my uncle for the first time in quite awhile. It was good to see him and he and my mom talked a bit about my college finances. It looks like they will be opening a couple more ING accounts with the money made going to my savings fund. That will be great since I earned quite a bit the last time I had an account opened.
My uncle also too some photos of me so that everyone can see how I have grown. It's hard for me to believe I'll be a year old in less than a month.


That last photo is me with mom. I look like a happy baby, don't I?
My uncle also too some photos of me so that everyone can see how I have grown. It's hard for me to believe I'll be a year old in less than a month.
That last photo is me with mom. I look like a happy baby, don't I?
Saturday, June 10, 2006
Been Awhile
Okay, it's been awhle since I have posted here, but my uncle is now back in the US and will be visiting me on a regular basis so there will be a lot more frequent updates and photos from now. This is exciting because i have lots of updates to talk about and now that he isn't moving and has settled down a bit, he'll have time to keep everyone up to date on my progress.
I'm looking forward to my first year birthday coming up in July which should help pad my savings a bit more. I als have to update on the profits I've made the last couple of months which I will do soon.
I'm still not talking, but am almost walking (^_^) - I stand myself up really well these days, but still need to balance against things to stay upright if I want to move around. It shouldn't be too much longer before I'm walking around on my own and then I really can get into all kinds of wonderful things.
Now that my uncle is back, I'll also have a much better opportunity to make some move with my college savings and increase my finances since it will be much easier for all of us to talk together. This should be a great improvement for my net worth and get me better prepared for college (since it is now only a bit more than 17 year before I'll be heading off). Good things with lots of information to post in the coming days...
I'm looking forward to my first year birthday coming up in July which should help pad my savings a bit more. I als have to update on the profits I've made the last couple of months which I will do soon.
I'm still not talking, but am almost walking (^_^) - I stand myself up really well these days, but still need to balance against things to stay upright if I want to move around. It shouldn't be too much longer before I'm walking around on my own and then I really can get into all kinds of wonderful things.
Now that my uncle is back, I'll also have a much better opportunity to make some move with my college savings and increase my finances since it will be much easier for all of us to talk together. This should be a great improvement for my net worth and get me better prepared for college (since it is now only a bit more than 17 year before I'll be heading off). Good things with lots of information to post in the coming days...
Sunday, May 14, 2006
Happy Mother's Day
I just wanted to take a moment to wish my Mom a very Happy Mother's Day!!!! This is her first one and I have to say that if life continues the way it has this first year, I'm going to be one happy kid. For all the times I woke you when you were sleeping, for all the times I spit out my food, for all the times I was cranky and for all the times I was just plain fussy, thanks for being my Mom and still looking out for me. Wishing you a wonderful day and a big thank you for all you do (to all Moms out there!)
Margot
Margot
Sunday, April 30, 2006
Reasons Not To Go To College
Now that I have gotten organized and started saving for college, Forbes.com comes up with five reasons why I shouldn't go to college that I should think about - this kind of throws a wrench into my well laid thoughts. Here are their five points:
Loss of 4 Years of Work
I Won't Necessarily Earn Less Money
I Could Probably Make More Money If I Invest My Tuition
A Classroom Isn't Needed To Learn Something
Plenty Of People Have Done Fine Without A College Education
These are certainly points to consider. Since I am planning to have my full tuition in my savings by the time I am ready to enter college, the investing point is especially noteworthy to me. That being said, I also know at my tender age that college isn't only about school work, but also the social aspect and the opportunity to try new things.
This is something I'll have to consider more as I get older and get a better idea of what I might like to do as a career.
These are certainly points to consider. Since I am planning to have my full tuition in my savings by the time I am ready to enter college, the investing point is especially noteworthy to me. That being said, I also know at my tender age that college isn't only about school work, but also the social aspect and the opportunity to try new things.
This is something I'll have to consider more as I get older and get a better idea of what I might like to do as a career.
Wednesday, April 12, 2006
Will My Money Have To Last Until I'm 150?
All the more reason for me to start saving at this early age. According to a report on the Today Show available on msn video, today's children may live up to 150 years old.
While I think this is great, it means that my retirement funds will have to be a lot bigger than if I assumed I'd only live to 80. An interesting possibility for my little mind to ponder.
While I think this is great, it means that my retirement funds will have to be a lot bigger than if I assumed I'd only live to 80. An interesting possibility for my little mind to ponder.
Monday, April 03, 2006
Some Numbers I Plan Not To be Part Of
The problem about reading about college and costs is that the numbers can get pretty depressing and I like being a cheerful little one. So instead of dwelling on the numbers, I have been proactive in making sure I'm not a part of the numbers that can be so depressing (thus this little blog). This is what I found today
Those are pretty depressing numbers even for a cheerful baby like me. it's just one more reason to make sure that you begin saving for college early which reminds me that I need to get my monthly numbers up - will be doing that soon.
According to Finaid.org "65.6 percent of students graduate with some debt." The median amount of debt owed once a student graduates is $17,120. Among graduating seniors, the average federal student loan debt is 19,202. Additional debt for graduate and professional degrees range from $27,000 to $114,000.
Those are pretty depressing numbers even for a cheerful baby like me. it's just one more reason to make sure that you begin saving for college early which reminds me that I need to get my monthly numbers up - will be doing that soon.
Sunday, April 02, 2006
Even At My Age I Have to Worry About Identity Theft
Boy, did my eyes pop wide open when I came across this bit of news. I figured at my age I had nothing to be worried about when it came to identity theft, but obviously I was wrong:
That's just crazy!
When a mother decided to open a savings account for her 18-month-old son this month, she was stunned to learn that someone else had beaten her to it.
Police say that a man with a record of identity fraud had taken the toddler's Social Security number and opened two accounts with Citizens Bank in Worcester and tried to obtain a Registry of Motor Vehicles identification card. By the time the boy's mother learned about the scam, the thief had deposited $19,000 in fraudulent checks, police said.
That's just crazy!
Friday, March 31, 2006
Other Resources
This is a page of other resources on the Internet that I and/or my uncle are involved with. As you can see, he is busy with a lot of projects, but they all do have a theme of saving money. there is a lot of quality information on them, so please visit and enjoy. You should be able to find a large number of ways to cut your costs and save more for yourself:
By looking through the grocery coupon money saving guide you'll learn how to save hundreds of dollars every month with grocery coupons.
Learn to garden without spending a lot at frugal gardening where you'll find tips and articles on ways to save money while still producing a wonderfully beautiful garden.
Help charities with a click of you mouse at charity click donation where you can give a simple click to help donate money to a wide variety of charities with no cost to you (advertisers pay). Included are bulk donators that can save you a large amount of time.
Most people don't realize the true cost of smoking which hurts your finances a lot more than the cost of the packs of cigarettes. These "hidden" costs include higher insurance rates, decreased value of assets, increased health care costs and reduced earning potential just to name a few.
While people often focus on the problems that credit cards cause, there are also many credit card advantages which can be leveraged if you use them wisely. Find out how credit cards can be used to your advantage and earn you money instead of cost you money.
If you need from basic to advance strategies on reducing debt, you can find it at Debt Reduction 101 which is a common sense guide to help you reduce your debt and get your personal finances in order.
Hybrid cars are becoming more and more popular and many come with a hybrid car tax deduction or credit. Find the latest information on these tax deductions and credits which you can receive for purchasing a hybrid car.
If you're looking for the latest I-Bond rate you can find it here along with other information about I-Bonds.
Dating doesn't have to be expensive to be fun. Learning how to do inexpensive dating will leave you with great memories and some money in your pocket as well.
While lawyers can be expensive, there are ways to find an inexpensive lawyer and to reduce the costs associated with hiring a lawyer.
Dieting and investing have a lot in common and invest diet highlights these areas. Learn to approach dieting like you would investments and investing like you would dieting. Lose weight and become financially secure at the same time.
*****************************
For those who have paid off their debt and are looking to increase their wealth can visit the investing page where they'll find basic investing strategies to grow your money.
While most people think of something else when they hear about National Condom Week, this site offers a way to protect yourself from debt with a free credit card condom.
Get the latest information on new tax deductions to help you save the most on your taxes.
If you want to make some extra money, take a look at some online auction hints that will help yuo maximize the amount of money you can make.
People are often interested when they hear that it can be possible to get paid to drive with auto wraps. here is the truth about them and what you need to do to get paid to drive.
If you can learn how to reduce college costs you can save a bundle on your education and even leave college debt free.
With rising medical costs, one place that you can save a lot of money is by learning how to reduce prescription costs and where to easily find these discounts.
One of the best ways to save money is to learn to do so by learning save money games so that you can save and have fun at the same time.
If you are looking for the latest tax information, you can find it at tax press release so that you're always on top of what changes are taking place at the IRS.
One of the worst investments you can make is to find yourself stuck in a timeshare trap and not know how to get out of it.
By looking through the grocery coupon money saving guide you'll learn how to save hundreds of dollars every month with grocery coupons.
Learn to garden without spending a lot at frugal gardening where you'll find tips and articles on ways to save money while still producing a wonderfully beautiful garden.
Help charities with a click of you mouse at charity click donation where you can give a simple click to help donate money to a wide variety of charities with no cost to you (advertisers pay). Included are bulk donators that can save you a large amount of time.
Most people don't realize the true cost of smoking which hurts your finances a lot more than the cost of the packs of cigarettes. These "hidden" costs include higher insurance rates, decreased value of assets, increased health care costs and reduced earning potential just to name a few.
While people often focus on the problems that credit cards cause, there are also many credit card advantages which can be leveraged if you use them wisely. Find out how credit cards can be used to your advantage and earn you money instead of cost you money.
If you need from basic to advance strategies on reducing debt, you can find it at Debt Reduction 101 which is a common sense guide to help you reduce your debt and get your personal finances in order.
Hybrid cars are becoming more and more popular and many come with a hybrid car tax deduction or credit. Find the latest information on these tax deductions and credits which you can receive for purchasing a hybrid car.
If you're looking for the latest I-Bond rate you can find it here along with other information about I-Bonds.
Dating doesn't have to be expensive to be fun. Learning how to do inexpensive dating will leave you with great memories and some money in your pocket as well.
While lawyers can be expensive, there are ways to find an inexpensive lawyer and to reduce the costs associated with hiring a lawyer.
Dieting and investing have a lot in common and invest diet highlights these areas. Learn to approach dieting like you would investments and investing like you would dieting. Lose weight and become financially secure at the same time.
*****************************
For those who have paid off their debt and are looking to increase their wealth can visit the investing page where they'll find basic investing strategies to grow your money.
While most people think of something else when they hear about National Condom Week, this site offers a way to protect yourself from debt with a free credit card condom.
Get the latest information on new tax deductions to help you save the most on your taxes.
If you want to make some extra money, take a look at some online auction hints that will help yuo maximize the amount of money you can make.
People are often interested when they hear that it can be possible to get paid to drive with auto wraps. here is the truth about them and what you need to do to get paid to drive.
If you can learn how to reduce college costs you can save a bundle on your education and even leave college debt free.
With rising medical costs, one place that you can save a lot of money is by learning how to reduce prescription costs and where to easily find these discounts.
One of the best ways to save money is to learn to do so by learning save money games so that you can save and have fun at the same time.
If you are looking for the latest tax information, you can find it at tax press release so that you're always on top of what changes are taking place at the IRS.
One of the worst investments you can make is to find yourself stuck in a timeshare trap and not know how to get out of it.
Sunday, March 26, 2006
Carnival of Personal Finance #41
Welcome to the 41st edition of the Carnival of Personal Finance. There is a wide variety of submissions this week and I'm certainly ready for a nap after going through all of them (and I didn't have to even read - something I still can't do - but just listen as they were being read). Still, it was worthwhile and will give you plenty of reading this week. Enjoy!
Banking
Money and Values: Community Development Banking
Quote: "I know it's not the absolute highest interest rate I could find, but it's a great balance for me personally. I'm happy knowing my money is having a positive social impact, and my savings are at least keeping a little ahead of inflation."
Mapgirl's Fiscal Challenge: Guaranteed 6% Rate of Return?
Quote: "It's participating in a social network of lending through the Korean community, called a 'geh'. Like the old Hibernian Banks and Building and Loan Societies of old, Korean folks raise capital through their social community networks."
Budgeting / Frugality
Thrifty Ray's Red to Black Journey: Whatever it Takes...
Quote: "'whatever it takes' was a very scary territory for me. My family was used to a lifestyle of spending. How could I get them to change?
"
No Credit Needed: How I Roll
Quote: "Imagine that the checking account is a glass full of water, and the saving account is an empty glass of water. I "pour" a bit of the cash from the checking account, every day or two, into the savings account. This way, I still have convenient access to my money, and I can chose NOT to transfer any amount of money at anytime. I like my system..."
Monkey Trouble: Since It's Been Discussed Elsewhere...
Quote: "Budget. The dirty 6 letter word that everyone hates with a passion. I was talking about my loosely defined budget with someone the other day. Basically this is the deal. I *hate* budgets. Hate 'em. I have good reason for hating them."
Flash's Saving Blog: Desperate Measures For Grocery Budgeting
Quote: "It's difficult. It may seem cruel. It may seem impossible. But when you force yourself to make choices, you start managing your budget."
Five Cent Nickel: Preparing For Our Moving Sale
Quote: "After seeing just how much crap we have, we actually debated about scrapping the sale entirely, and just donating everything to charity ? after all, that would save us the pain of pricing it all. But we ultimately rallied (here again, ‘we’ should be interpreted as my lovely and talented wife) and now have a garage full of stuff that is mostly priced."
Debt Hater: Paying Yourself First, For Real
Quote: "When I budgeted what I "paid myself" it was really easy to simply change that when I ran low on cash. But if I never counted that money to begin with and knew I couldn't just transfer it out of savings, I'd be forced to be a lot smarter about my money."
Common Room: Cost Versus Value
Quote: "So we loaded that heavy thing on the truck (we moved ourselves), friends had to unload it (because we were stranded in a Midwestern state hoping the Headmaster would regain the use of his arm after the car accident en route), and we've never needed it, never will need it, and have no place for it. It would have been more cost effective to leave it behind."
Boston Gal's Open Wallet: The Decisions Involved In Spending Money
Quote: "As I mentioned in my post: My decor is more Sanford & Son less Martha Stewart, I really do struggle with this. I guess it comes down to - I want nice things, I just don't want to pay for them."
2¢ Worth: Gadget Freebies
Quote: "It isn't about comparing like to like. You have to compare it with what you're currently having - and whether there's a burning need to change the status quo."
Career / Work
Find A New Job: The Value Of A Vacation Week
Quote: "No matter what people tell you, vacation time is negotiable, but some times it is not worth to negotiate it."
Career Intensity Blog: Three Steps To A New Career
Quote: "Managing your career is hard work. It is probably the most important thing you can do. If you do not take control of your career you will be subject to the never-ending cycle of unproductive performance reviews and less than thrilling salary increases. "
Aridni: Today's Office Special: Free Money
Quote: "Martha Stewart would say, "It's a good thing." Meanwhile, I'm still dreaming of that free money at my fingertips."
Credit / Debt
Pacesetter Mortgage Blog: Credit Bureaus Agree To Common Credit Scoring System
Quote: "To this end, the three credit reporting agencies have just announced VantageScore. The VantageScore is a proprietary score, developed by the three credit reporting agencies, designed to compete directly with the FICO score."
Ozarklad: Negotiating Down Credit Card Rates
Quote: "On Saturday I received yet another offer of a loan from that bank, this time for 7.99%. So Monday morning I called again. This time the person ran through various questions, such as salary, rent vs. own, etc. She offered 19.99, which is much better than the others, but it's still in what I would consider a sub-prime rate. I accepted the new rate, because it is reduced 7.5%."
Our Money Matters: Spot a Bad Credit Card Offer Without Reading It
Quote: "If the offer is for a MasterCard or Visa and includes a fake credit card, the terms and conditions are always bad."
Net Worth Blog: The Higher Yield Files: Valuing Leverage
Quote: "It's pretty straightforward to calculate. Just line up your assets and the return you expect to generate from each, line up your liabilities and their respective costs. The difference in returns is your net return and that divided by your net worth is your return on (beginning) equity ("ROE")."
Frank the Financially Savvy Atheist (The F.S.A.): How Credit Card Companies Make Money
Quote: "This presents something of a quandary for the Credit Card companies. They don't necessarily want to tie up $1 trillion dollars worth of capital all the time. Even though they can charge interest rates in the 20%+ range, they're are other things that they want to do with their capital."
Health / Medical
Single Guy High Impact Saving: High Impact Savings My Way
Quote: "You've probably heard that exercising is good for you, but you haven't really considered all the benefits (health and money wise) you can get from it."
InsureBlog: What Price Cancer?
Quote: "This paradox is what is confusing, even to those who seemingly understand the yin and yang of health care. One (drug) has low demand, so the price is inflated. The other (drug) has high demand, so the price is inflated."
Hayek, MD: Welcome To The Jungle
Quote: "Interpretation: Passing Health Savings Accounts legislation was like drafting children to fight in Vietnam or, wait for it, like Bush drafting children for his War in Iraq - did you see that sneeky sleight-of-hand?"
Investing
Laws of Finance: Dollar Doomed? Diversify Abroad!
Quote: "Basically, foreigners frantically ridding themselves of U.S. dollars and U.S. dollar denominated assets will send the dollar plunging. As I said before, asset prices will also plummet. So, your savings may not be as secure as you think it is if you have it in U.S. dollar denominated assets. This could lead to a rash of bankruptcies. Hmmm… Maybe I should look into bankruptcy law. I think there might be a killing to be made there in a few years."
It's Just Money: ABCs of Mutual Fund Loads
Quote: "One of the biggest problems is that the clever load funds vary the way that they charge you. This way, if you are looking for the front load, you may not find it, yet still get charged the same amount or more."
Investing Guide: Vanguard Portfolio
Quote: "I am thinking about tweaking the portfolio a little more, but I think this portfolio will do for now. Slice and dicing a portfolio seems like a lot of trouble, but at least it gives investors more control of their asset."
Frugal Wisdom From Wenchypoo's Warehouse: Let's Play The Bird Flu Strategy Game!
Quote: "The Bird Flu makes me wish there was some sort of a meat index. I hate having to buy individual stocks, but I see no other way to take advantage of this occurrence."
Financial Reference: Expected Returns
Quote: "The calculation that should be used is to value the company using a discounted cash flow analysis (whether it’s discounted dividends, free cash flow, etc.) to arrive at a current value for the company and it’s shares. You can then calculate a value for the company at any date in the future using the same assumptions you used in your initial calculation."
Financial Options: Your Financial Roadmap for March 27-31, 2006
Quote: "The earnings releases listed are companies I've chosen because of their industries, because of market capitalization (the size of the company), because they have local plants in my area or for various other reasons of general interest."
Dividend Guy: Stock Analysis - My Approach with GE
Quote: "The important thing to consider about the whole process (whether you are using a software package or not) is that the decision to buy a company is based totally on your interpretation of the data."
Ask Uncle Bill: Market Psychology or The Wall Of Worry
Quote: "So the market should go down because there are a lot of things to worry about. Guess what, there are always a lot of things to worry about and, in the past, a lot more worrisome things than those things listed above."
Personal Finance
Journey To Financial Freedom: Things You Must Do To Achieve Financial Freedom
Quote: "Maybe because of my improvements or because I spend a lot of time with my mentor, suddenly I can see the other side of the world. A world of people who are financial free. This has really helped me so I can analyze and compare and finally I found that there are some things that my mentor always does that other people may take for granted."
"D"igital Breakfast: Sun Tzu and the Art of Personal Finance (III)
Quote: "As many of us knows, success in personal finance is derived from laying plans. I had a project manager once tell me to always remember the 6P’s: Proper Planning Prevents Piss Poor Performance. So regardless of what you want to do in life and how you want your finances to turn out, if you don’t plan you plan to fail. Boy did I just cliche myself through this paragraph!"
Adult ADD and Money: Reasons To Play The Lottery
Quote: "Playing the lottery on a regular basis is a bad financial strategy. Statistically you will get a negative return for the money that you invest in playing the lottery. However if you just focused on these three reasons you might be inclined to make the lottery part of your investing portfolio."
Real Estate / Mortgages
Searchlight Crusade: Lenders Are All The Same
Quote: "Just like Mohandas Gandhi and Genghis Khan and Attila the Hun were all human beings, lenders make money by lending money to people who want it. That's about the limit of the truth in that statement."
Million Dollar Goal: An Introduction To FHA Loan Benefits
Quote: "Many people, especially first-time buyers, use FHA loans because the qualifications are a bit more lenient and they can purchase a house with a 3-percent down payment. While it is possible to get a 3-percent down payment for a conventional loan -- and even zero-down loans -- interest rates are normally higher than with FHA-backed loans."
Blueprint for Financial Prosperity: Do You Care About Housing Market Signs?
Quote: "I believe the only place national stats matter is when you're talking mortgage loan rates and the housing market lags mortgage rates. The rates are going up, that's why housing sales are decreasing, it's not the other way around. So really, I don't think national stats matter at all when you're thinking about selling or buying a home...the local stats matter significantly more."
Shopping / Buying
Single Ma's Fabulous Financials: The Art Of Negotiating
...when buying a new(er) car
Quote: "...it only works if you're not in desperate need for a car because the entire process takes time. Helpful Tip: Do NOT wait until your car leaves you stranded on the side of the road before deciding to replace it."
Inchoate Random Abstractions: Appearances Can Be Deceiving
Quote: "How well-dressed you are is one indicator of your status, and how much money you have to spend. Makes sense, right? But so not true! If any of you have read the Millionaire Next Door, you'll know what I'm talking about."
Canadian Financial Stuff: Rant: Poor Customer Service
Quote: "Moral of this rant, don't stand for being treated like cattle, or worse still vermin, when you are going to drop a couple of hundred dollars on any item. You are spending your hard earned money, make the sales people treat you well, to earn their commission (or whatever sales pay they receive)."
A Geek's World: A Good Deal From Consumer Reports
Quote: "I do not think I would recommend making a big buy without getting (Consumer Report's) opinion. At the very least you will find out the positives and negatives of what you are buying."
Taxes
Sitting Pretty: Getting Ahead At Tax Time
Quote: "There isn’t any legal way out of paying taxes. So it’s best to just succumb to the inevitable and do your patriotic part. However, the law-abiding approach is going to leave you struggling like millions of other middle class Americans."
Roth & Company Tax Update: You Made A deal With American Express: Here Comes The IRS
Quote: "When you cut a deal on your credit card debt, put aside something for the tax man. They don't go for for the "I didn't get the 1099-C" ploy."
Multiple Mentality: Random "Tax Refund" Rant
Quote: "Admittedly, if there was no withholding, people wouldn't have enough money to pay their taxes because the preponderance of us (including myself) can't budget our money properly (hence the overabundance of credit card debt in this country), but I still find it unfair that we’re not allowed to create our own "income tax savings account" if we want to, have our money withheld in a bank of our own choosing, and then cut a check to the government in the first quarter of the next year."
Mighty Bargain Hunter: When That Interest-Free Loan Gets Paid Back
Quote: "When I saw the Liz Pulliam Weston article "7 smart ways to spend your tax refund" I saw the word "spend" and thought, "Oh great, just blow it on junk, why don't you!" But I was wrong in this assumption."
Don't Mess With Taxes: The Slings And Arrows Of Outrageous Taxes
Quote: "Poor Ellen. She's learned a sad fact. Tax collectors the world over are insistent on accuracy. They also want substantiation. Among the things that got Ellen in trouble was trying to write off too many things as business expenses when in reality they had only a vague, quasi-legitimate connection to her job."
Centrerion: How to Do Your Taxes Faster
Quote: "On looseleaf, you should write things such as which sections will see the numbers increase or decrease. This means accidental errors will be caught before the end of the process (last year, I added 9K where I was supposed to substract... you can imagine my surprise when I finished and saw that I, a student, owed money to the government!)"
Cap'n Arbyte's: It's Good to Doublecheck
Quote: "As much as I detest knowing anything about taxes, in this instance I think my meager knowledge saved me from an audit. The IRS would know about those sales, but they weren't on my tax returns! As repellent as it is to waste my mental capacity with information about taxes, I think an audit would be even more horrible. "
Canadian Capitalist: Over Withholding
Quote: "To find out how much the interest-free loan cost me, I ran a quick calculation: Let's say I am expecting a $6,000 refund on my taxes, which works out to $500 per month. I am also assuming that I can get a 5% risk-free, tax-free return by making a lump-sum prepayment on our mortgage. That works out to $216.45 in lost interest over a period of 15 months."
Time Management
Firevalt: Law of Lost Attention
Quote: "Learning to focus my attention on the worthwhile will bring me the success I seek. In our day and age of mult-tasking, we divide our attention over many trivial things, and focus less on the things that will bring satisfaction and meaning."
That’s it for this week. I hope you enjoyed the reading. Next week’s Carnival of Personal Finance will be hosted at okdork and you can find out more information and the entire schedule at Consumerism Commentary
Banking
Money and Values: Community Development Banking
Quote: "I know it's not the absolute highest interest rate I could find, but it's a great balance for me personally. I'm happy knowing my money is having a positive social impact, and my savings are at least keeping a little ahead of inflation."
Mapgirl's Fiscal Challenge: Guaranteed 6% Rate of Return?
Quote: "It's participating in a social network of lending through the Korean community, called a 'geh'. Like the old Hibernian Banks and Building and Loan Societies of old, Korean folks raise capital through their social community networks."
Budgeting / Frugality
Thrifty Ray's Red to Black Journey: Whatever it Takes...
Quote: "'whatever it takes' was a very scary territory for me. My family was used to a lifestyle of spending. How could I get them to change?
"
No Credit Needed: How I Roll
Quote: "Imagine that the checking account is a glass full of water, and the saving account is an empty glass of water. I "pour" a bit of the cash from the checking account, every day or two, into the savings account. This way, I still have convenient access to my money, and I can chose NOT to transfer any amount of money at anytime. I like my system..."
Monkey Trouble: Since It's Been Discussed Elsewhere...
Quote: "Budget. The dirty 6 letter word that everyone hates with a passion. I was talking about my loosely defined budget with someone the other day. Basically this is the deal. I *hate* budgets. Hate 'em. I have good reason for hating them."
Flash's Saving Blog: Desperate Measures For Grocery Budgeting
Quote: "It's difficult. It may seem cruel. It may seem impossible. But when you force yourself to make choices, you start managing your budget."
Five Cent Nickel: Preparing For Our Moving Sale
Quote: "After seeing just how much crap we have, we actually debated about scrapping the sale entirely, and just donating everything to charity ? after all, that would save us the pain of pricing it all. But we ultimately rallied (here again, ‘we’ should be interpreted as my lovely and talented wife) and now have a garage full of stuff that is mostly priced."
Debt Hater: Paying Yourself First, For Real
Quote: "When I budgeted what I "paid myself" it was really easy to simply change that when I ran low on cash. But if I never counted that money to begin with and knew I couldn't just transfer it out of savings, I'd be forced to be a lot smarter about my money."
Common Room: Cost Versus Value
Quote: "So we loaded that heavy thing on the truck (we moved ourselves), friends had to unload it (because we were stranded in a Midwestern state hoping the Headmaster would regain the use of his arm after the car accident en route), and we've never needed it, never will need it, and have no place for it. It would have been more cost effective to leave it behind."
Boston Gal's Open Wallet: The Decisions Involved In Spending Money
Quote: "As I mentioned in my post: My decor is more Sanford & Son less Martha Stewart, I really do struggle with this. I guess it comes down to - I want nice things, I just don't want to pay for them."
2¢ Worth: Gadget Freebies
Quote: "It isn't about comparing like to like. You have to compare it with what you're currently having - and whether there's a burning need to change the status quo."
Career / Work
Find A New Job: The Value Of A Vacation Week
Quote: "No matter what people tell you, vacation time is negotiable, but some times it is not worth to negotiate it."
Career Intensity Blog: Three Steps To A New Career
Quote: "Managing your career is hard work. It is probably the most important thing you can do. If you do not take control of your career you will be subject to the never-ending cycle of unproductive performance reviews and less than thrilling salary increases. "
Aridni: Today's Office Special: Free Money
Quote: "Martha Stewart would say, "It's a good thing." Meanwhile, I'm still dreaming of that free money at my fingertips."
Credit / Debt
Pacesetter Mortgage Blog: Credit Bureaus Agree To Common Credit Scoring System
Quote: "To this end, the three credit reporting agencies have just announced VantageScore. The VantageScore is a proprietary score, developed by the three credit reporting agencies, designed to compete directly with the FICO score."
Ozarklad: Negotiating Down Credit Card Rates
Quote: "On Saturday I received yet another offer of a loan from that bank, this time for 7.99%. So Monday morning I called again. This time the person ran through various questions, such as salary, rent vs. own, etc. She offered 19.99, which is much better than the others, but it's still in what I would consider a sub-prime rate. I accepted the new rate, because it is reduced 7.5%."
Our Money Matters: Spot a Bad Credit Card Offer Without Reading It
Quote: "If the offer is for a MasterCard or Visa and includes a fake credit card, the terms and conditions are always bad."
Net Worth Blog: The Higher Yield Files: Valuing Leverage
Quote: "It's pretty straightforward to calculate. Just line up your assets and the return you expect to generate from each, line up your liabilities and their respective costs. The difference in returns is your net return and that divided by your net worth is your return on (beginning) equity ("ROE")."
Frank the Financially Savvy Atheist (The F.S.A.): How Credit Card Companies Make Money
Quote: "This presents something of a quandary for the Credit Card companies. They don't necessarily want to tie up $1 trillion dollars worth of capital all the time. Even though they can charge interest rates in the 20%+ range, they're are other things that they want to do with their capital."
Health / Medical
Single Guy High Impact Saving: High Impact Savings My Way
Quote: "You've probably heard that exercising is good for you, but you haven't really considered all the benefits (health and money wise) you can get from it."
InsureBlog: What Price Cancer?
Quote: "This paradox is what is confusing, even to those who seemingly understand the yin and yang of health care. One (drug) has low demand, so the price is inflated. The other (drug) has high demand, so the price is inflated."
Hayek, MD: Welcome To The Jungle
Quote: "Interpretation: Passing Health Savings Accounts legislation was like drafting children to fight in Vietnam or, wait for it, like Bush drafting children for his War in Iraq - did you see that sneeky sleight-of-hand?"
Investing
Laws of Finance: Dollar Doomed? Diversify Abroad!
Quote: "Basically, foreigners frantically ridding themselves of U.S. dollars and U.S. dollar denominated assets will send the dollar plunging. As I said before, asset prices will also plummet. So, your savings may not be as secure as you think it is if you have it in U.S. dollar denominated assets. This could lead to a rash of bankruptcies. Hmmm… Maybe I should look into bankruptcy law. I think there might be a killing to be made there in a few years."
It's Just Money: ABCs of Mutual Fund Loads
Quote: "One of the biggest problems is that the clever load funds vary the way that they charge you. This way, if you are looking for the front load, you may not find it, yet still get charged the same amount or more."
Investing Guide: Vanguard Portfolio
Quote: "I am thinking about tweaking the portfolio a little more, but I think this portfolio will do for now. Slice and dicing a portfolio seems like a lot of trouble, but at least it gives investors more control of their asset."
Frugal Wisdom From Wenchypoo's Warehouse: Let's Play The Bird Flu Strategy Game!
Quote: "The Bird Flu makes me wish there was some sort of a meat index. I hate having to buy individual stocks, but I see no other way to take advantage of this occurrence."
Financial Reference: Expected Returns
Quote: "The calculation that should be used is to value the company using a discounted cash flow analysis (whether it’s discounted dividends, free cash flow, etc.) to arrive at a current value for the company and it’s shares. You can then calculate a value for the company at any date in the future using the same assumptions you used in your initial calculation."
Financial Options: Your Financial Roadmap for March 27-31, 2006
Quote: "The earnings releases listed are companies I've chosen because of their industries, because of market capitalization (the size of the company), because they have local plants in my area or for various other reasons of general interest."
Dividend Guy: Stock Analysis - My Approach with GE
Quote: "The important thing to consider about the whole process (whether you are using a software package or not) is that the decision to buy a company is based totally on your interpretation of the data."
Ask Uncle Bill: Market Psychology or The Wall Of Worry
Quote: "So the market should go down because there are a lot of things to worry about. Guess what, there are always a lot of things to worry about and, in the past, a lot more worrisome things than those things listed above."
Personal Finance
Journey To Financial Freedom: Things You Must Do To Achieve Financial Freedom
Quote: "Maybe because of my improvements or because I spend a lot of time with my mentor, suddenly I can see the other side of the world. A world of people who are financial free. This has really helped me so I can analyze and compare and finally I found that there are some things that my mentor always does that other people may take for granted."
"D"igital Breakfast: Sun Tzu and the Art of Personal Finance (III)
Quote: "As many of us knows, success in personal finance is derived from laying plans. I had a project manager once tell me to always remember the 6P’s: Proper Planning Prevents Piss Poor Performance. So regardless of what you want to do in life and how you want your finances to turn out, if you don’t plan you plan to fail. Boy did I just cliche myself through this paragraph!"
Adult ADD and Money: Reasons To Play The Lottery
Quote: "Playing the lottery on a regular basis is a bad financial strategy. Statistically you will get a negative return for the money that you invest in playing the lottery. However if you just focused on these three reasons you might be inclined to make the lottery part of your investing portfolio."
Real Estate / Mortgages
Searchlight Crusade: Lenders Are All The Same
Quote: "Just like Mohandas Gandhi and Genghis Khan and Attila the Hun were all human beings, lenders make money by lending money to people who want it. That's about the limit of the truth in that statement."
Million Dollar Goal: An Introduction To FHA Loan Benefits
Quote: "Many people, especially first-time buyers, use FHA loans because the qualifications are a bit more lenient and they can purchase a house with a 3-percent down payment. While it is possible to get a 3-percent down payment for a conventional loan -- and even zero-down loans -- interest rates are normally higher than with FHA-backed loans."
Blueprint for Financial Prosperity: Do You Care About Housing Market Signs?
Quote: "I believe the only place national stats matter is when you're talking mortgage loan rates and the housing market lags mortgage rates. The rates are going up, that's why housing sales are decreasing, it's not the other way around. So really, I don't think national stats matter at all when you're thinking about selling or buying a home...the local stats matter significantly more."
Shopping / Buying
Single Ma's Fabulous Financials: The Art Of Negotiating
...when buying a new(er) car
Quote: "...it only works if you're not in desperate need for a car because the entire process takes time. Helpful Tip: Do NOT wait until your car leaves you stranded on the side of the road before deciding to replace it."
Inchoate Random Abstractions: Appearances Can Be Deceiving
Quote: "How well-dressed you are is one indicator of your status, and how much money you have to spend. Makes sense, right? But so not true! If any of you have read the Millionaire Next Door, you'll know what I'm talking about."
Canadian Financial Stuff: Rant: Poor Customer Service
Quote: "Moral of this rant, don't stand for being treated like cattle, or worse still vermin, when you are going to drop a couple of hundred dollars on any item. You are spending your hard earned money, make the sales people treat you well, to earn their commission (or whatever sales pay they receive)."
A Geek's World: A Good Deal From Consumer Reports
Quote: "I do not think I would recommend making a big buy without getting (Consumer Report's) opinion. At the very least you will find out the positives and negatives of what you are buying."
Taxes
Sitting Pretty: Getting Ahead At Tax Time
Quote: "There isn’t any legal way out of paying taxes. So it’s best to just succumb to the inevitable and do your patriotic part. However, the law-abiding approach is going to leave you struggling like millions of other middle class Americans."
Roth & Company Tax Update: You Made A deal With American Express: Here Comes The IRS
Quote: "When you cut a deal on your credit card debt, put aside something for the tax man. They don't go for for the "I didn't get the 1099-C" ploy."
Multiple Mentality: Random "Tax Refund" Rant
Quote: "Admittedly, if there was no withholding, people wouldn't have enough money to pay their taxes because the preponderance of us (including myself) can't budget our money properly (hence the overabundance of credit card debt in this country), but I still find it unfair that we’re not allowed to create our own "income tax savings account" if we want to, have our money withheld in a bank of our own choosing, and then cut a check to the government in the first quarter of the next year."
Mighty Bargain Hunter: When That Interest-Free Loan Gets Paid Back
Quote: "When I saw the Liz Pulliam Weston article "7 smart ways to spend your tax refund" I saw the word "spend" and thought, "Oh great, just blow it on junk, why don't you!" But I was wrong in this assumption."
Don't Mess With Taxes: The Slings And Arrows Of Outrageous Taxes
Quote: "Poor Ellen. She's learned a sad fact. Tax collectors the world over are insistent on accuracy. They also want substantiation. Among the things that got Ellen in trouble was trying to write off too many things as business expenses when in reality they had only a vague, quasi-legitimate connection to her job."
Centrerion: How to Do Your Taxes Faster
Quote: "On looseleaf, you should write things such as which sections will see the numbers increase or decrease. This means accidental errors will be caught before the end of the process (last year, I added 9K where I was supposed to substract... you can imagine my surprise when I finished and saw that I, a student, owed money to the government!)"
Cap'n Arbyte's: It's Good to Doublecheck
Quote: "As much as I detest knowing anything about taxes, in this instance I think my meager knowledge saved me from an audit. The IRS would know about those sales, but they weren't on my tax returns!
Canadian Capitalist: Over Withholding
Quote: "To find out how much the interest-free loan cost me, I ran a quick calculation: Let's say I am expecting a $6,000 refund on my taxes, which works out to $500 per month. I am also assuming that I can get a 5% risk-free, tax-free return by making a lump-sum prepayment on our mortgage. That works out to $216.45 in lost interest over a period of 15 months."
Time Management
Firevalt: Law of Lost Attention
Quote: "Learning to focus my attention on the worthwhile will bring me the success I seek. In our day and age of mult-tasking, we divide our attention over many trivial things, and focus less on the things that will bring satisfaction and meaning."
That’s it for this week. I hope you enjoyed the reading. Next week’s Carnival of Personal Finance will be hosted at okdork and you can find out more information and the entire schedule at Consumerism Commentary
Student Financial Literacy
I know that I'm an early starter when it comes to saving money and I'm hoping that my example can help others become early starters too. When I read the news (okay, I still can't read, but you know what I mean) the numbers for students who understand about finances isn't too good. Here is some information I ran across today:
The good news seems to be that more high schools are beginning to offer personal finance classes for the students. That seems to me to be once subject area where you can't go wrong in passing on knowledge. I hope to see more and more articles like the one above and see more parents learn that giving money to their children without also teaching them the responsibilities in how to use it is one of the biggest disservices they can do for them. (wow, I can already go off on a rant at this tender age...kind of scary what I'll be doing in a bit when I can talk)
In a survey conducted by Visa USA, 78 percent of parents said their high school student does not have a budget. And while 62 percent said they require their teens to save at least some of what they earn, more than half (57 percent) place no restrictions on how their children can spend the money they are given...
A national survey conducted last year revealed that the nation's high school seniors scored an average of 52.3 percent when tested about their knowledge of personal finance concepts.
The good news seems to be that more high schools are beginning to offer personal finance classes for the students. That seems to me to be once subject area where you can't go wrong in passing on knowledge. I hope to see more and more articles like the one above and see more parents learn that giving money to their children without also teaching them the responsibilities in how to use it is one of the biggest disservices they can do for them. (wow, I can already go off on a rant at this tender age...kind of scary what I'll be doing in a bit when I can talk)
Monday, March 20, 2006
Personal Finance Classes In High School
While I'm taking the quick route to learning about personal finances, there are still a lot of parents that don't teach. While I hope that since you are visiting here that you will begin teaching your child about money from a young age, I think that schools also need to do a better job (look at me, already critiquing the education system and I haven't even entered preschool let alone learned to walk). While personal finance education is still lacking to a huge degree, there are small signs of hope. I found this article about a school that is teaching personal finances:
I think that is a wonderful step in the right direction. The following quote summed up what is happening in many of our schools today:
I hope that more school districts take on this attitude as being educated in personal finances could be worth even more than a college education if it keeps the person from making basic financial mistakes in their lifetime.
The Delaware Community School board feels a money management course is so important that the board will require students to take personal finance starting with the class of 2010. The course is now an elective, but because students have to take college preparatory courses the number of students who take the elective is low, Principal Greg Hinshaw said.
I think that is a wonderful step in the right direction. The following quote summed up what is happening in many of our schools today:
"Sometimes I feel like were preparing everyone to go to college, which is great, but those everyday things (basics like personal finance) are getting left behind."
I hope that more school districts take on this attitude as being educated in personal finances could be worth even more than a college education if it keeps the person from making basic financial mistakes in their lifetime.


College Costs Could Double By 2020
Here's a piece that says that college costs could double by 2020 and that 529 Savings Plans aren't performing as well as most had hoped.
See The Video
See The Video
Friday, March 10, 2006
Cost of College Calculator
Here is a nice little calculator that will tell you the annual cost of any 4 year college in the USA:
College Cost Finder Calculator
College Cost Finder Calculator
Thursday, March 09, 2006
Helping My Uncle Out - ReduceCollegeCosts.com
After having a discussion (well, I'm getting better at listening, but I still much prefer a rattle or my favorite toy waved in front of my face)with my uncle, I've decided to help him out with one of his new websites. It has just been placed up so it doesn't have an extensive amount of information at the moment, but I hope that with my help it will grow into a well-stocked site with hundreds of tips on how to reduce the expenses associated with college. The name of the site is Reduce College Costs and I plan to go through this journal over the weekend with him to pick out some more college money saving tips to add.
If any of you have good tips that you have used or heard of, please leave them here in the comment section or send me an email so we can add to those already listed.
If any of you have good tips that you have used or heard of, please leave them here in the comment section or send me an email so we can add to those already listed.
Saturday, March 04, 2006
Free Five 2-Liter Coke Bottles
If you drink Coke or Coke products, here is another one that can save you some money. A big thanks to KarenSue for pointing this one out. Your chance to win 5 free 2-liter bottles of Coke - I tried it and already won 5 free bottles! (although I'm too young to get addicted to these yet, so I'll pass them onto my parents). If you drink these and win (you have 30 chances if you play daily since the contest ends on March 15) you can add the cost of the bottles to your college fund. I would say from the comments of those playing the game so far you will receive at least 5 bottles, and likely many more. Here's the explanation
olympics.coke.com
You don't need to buy the products - they will e-mail you free codes with which to play with. You can enter three times each day. The first day I tried I didn't win, but last night I won twice in a row! The participating products are all kinds of Coke, Dasani, Minute Maid Refreshment, Minute Maid Lite, and Nestea Cool.
Here's how to do it. Go to the Coke website and click on the Enter Codes link. You'll need to register on the site, but you only have to do that once. Then look for a graphic at the bottom of the page that says "Where's my code?" Click on that link and after entering a security code, you will be emailed a free code. If you copy and paste the code from the e-mail to the contest site, you need to remove the two spaces in the code and add the last two code numbers. Any problems or questions, I'll be happy to help.
Good luck and don't forget to donate to the college fund any savings!
Free Smart Money Magazine
 I have mentioned a number of times that one way to build a college fund is to get things for free and place the amount you would have had to pay for it into a college fund. Here's another one you can do. You can get a free subscription to Smart Money magazine (my uncle enjoys reading it and finds some good money saving tips in it) - and if you find ways to save from the magazine, you can place the difference into your college fund. If you don't, you still get a free magazine with good personal finance articles at no cost (^_^). These promotions usually don't last long, so get it while you can.
A New Name
I will be moving sometime in the next few months - I'm not exactly sure when this will be as I'm not in a big hurry, but I will be sometime soon. Why do you ask? My uncle decided that instead of staying on a free site that I should get my own name. He tried very hard to get me financialbabysteps.com, but the owner wasn't interested in selling the name. I'm learning young in life that you can't always get what you want.
While you can't always get what you want, that doesn't mean you should sit around and feel sorry for yourself. Once it became clear that our number one name wasn't going to be available, we started talking about other names that might be appropriate. We finally decided on financialbabe.com. my uncle said that he would give me the name as a gift so it doesn't hurt my net worth. Now not only am I working on my finances, I feel like I'm a true Internet entrepreneur with my own domain name to come into service in the next few months.
While you can't always get what you want, that doesn't mean you should sit around and feel sorry for yourself. Once it became clear that our number one name wasn't going to be available, we started talking about other names that might be appropriate. We finally decided on financialbabe.com. my uncle said that he would give me the name as a gift so it doesn't hurt my net worth. Now not only am I working on my finances, I feel like I'm a true Internet entrepreneur with my own domain name to come into service in the next few months.
February Net Worth
What a month will do. Not only can I crawl backward (which I was doing with acclaim last month), I can now crawl forward in a pretty impressive manner. Even better, I am way into textures these days. Boy, is it fun being a baby!
First and foremost, I passed the magic $3000 net worth mark (woohoo!!!) with my current net worth now adding up to $3015.82. That is well below the 5% increase in net worth that I was shooting for, but was just over a 3% gain for the month.
The best part of the gain was that most of it was from advertising - $80.37. $29.85 was a one time payment for three months, but about $50 is money that will continue to come on a monthly basis! If I can keep a minimum of $50 a month in advertising coming in, that will add up to more than $10,000 toward my college fund not counting any interest. I'm extremely happy with that development.
I will still stick with my goal of increasing my net worth by 5% a month which would mean adding about $150 to my current total. So I will be shooting for $3165 by the end of March.
First and foremost, I passed the magic $3000 net worth mark (woohoo!!!) with my current net worth now adding up to $3015.82. That is well below the 5% increase in net worth that I was shooting for, but was just over a 3% gain for the month.
The best part of the gain was that most of it was from advertising - $80.37. $29.85 was a one time payment for three months, but about $50 is money that will continue to come on a monthly basis! If I can keep a minimum of $50 a month in advertising coming in, that will add up to more than $10,000 toward my college fund not counting any interest. I'm extremely happy with that development.
I will still stick with my goal of increasing my net worth by 5% a month which would mean adding about $150 to my current total. So I will be shooting for $3165 by the end of March.
Friday, March 03, 2006
College & Credit Cards
I came across this video about college students and credit cards that was made by a college student. It's a bit long, but it does have interviews with some college students about their thoughts on credit cards. The best line?
"Get free stuff (for filling out credit card applications)and in return get a lifetime of debt"
This is one more reason to teach your kids well about money management, personal finances and credit card use before they try and learn on their own.
"Get free stuff (for filling out credit card applications)and in return get a lifetime of debt"
This is one more reason to teach your kids well about money management, personal finances and credit card use before they try and learn on their own.
Saturday, February 18, 2006
Baby Calculator

When it comes to having a baby, creating a financial plan and budgeting are a huge issue. A new survey from VISA finds that 76% of expectant parents considered themselves financially prepared without realizing what being financial prepared entailed. More than half of all new parents overspent on baby items. They also claimed that tension in their relationships created more stress for both parents.
One of the most costly aspects of having a child was for the actual delivery. Over a quarter of new parents shelled out over $2000 out of their own pockets for the delivery.
The U.S. Department of Agriculture estimates that an average American family will spend $184,000 raising a child and this doesn't include college costs. There is a new Baby Budgeting Calculator that can help parents predict the true cost of raising a baby.
Having a good financial plan and one that reflects reality is an important part of being able to put aside some extra money for your kids' education.
Friday, February 17, 2006
HAPPY BIRTHDAY MOM!!

Today is my mom's birthday and I just wanted to take a moment to say Happy Birthday and to say how thankful I am to have been born into such a wonderful family. Even on my worst days when I'm cranking and crying, it's unbelievable how patient she is with me. I really do appreaciate that. I can't think of a better person to have as my mom. So here's to you, mom, hoping that you have a wonderful day!
Happy birthday to you
happy birthday to you
Happy birthday dear mom
Happy birthday to you!
Love
Margot
Moms With Babies - Another Sign-Up Link
I expect that the pinecone research link below will expire fairly soon, but I found another specifically for moms with babies. Now, this is just an assumption on my part, but I'm guessing that a few of the visitors here fir that description. Here is the information:
PineCone Research is ready to expand and we need your help.
We have immediate openings for MOMS OF BABIES 12 MONTHS OF AGE OR YOUNGER.
Do you know of households that meet this description that would like to join the PineCone Research Panel? If so, please FORWARD A COPY of this e-mail to each household you would like to refer so that they may click on the registration link shown below. That household should complete the registration form themselves and submit it. REMEMBER THAT ONLY ONE PERSON PER HOUSEHOLD MAY REGISTER.
Multiple registrations of the same Household will void all registrations.
Here is the link to the registration:
Sign Up Here
Remember to place any earnings in to the college fund!
PineCone Research is ready to expand and we need your help.
We have immediate openings for MOMS OF BABIES 12 MONTHS OF AGE OR YOUNGER.
Do you know of households that meet this description that would like to join the PineCone Research Panel? If so, please FORWARD A COPY of this e-mail to each household you would like to refer so that they may click on the registration link shown below. That household should complete the registration form themselves and submit it. REMEMBER THAT ONLY ONE PERSON PER HOUSEHOLD MAY REGISTER.
Multiple registrations of the same Household will void all registrations.
Here is the link to the registration:
Sign Up Here
Remember to place any earnings in to the college fund!
Thursday, February 16, 2006
New Sponsor
Woo hoo! I'm a happy baby this morning (all smiles and giggles even without touching my nose - I like it when my parents do that). I just found out that I have another sponsor that has come aboard for 3 months and added $29.85 to my net worth. I hope that I can continue to find more that will be willing to sponsor to build the college fund. If I can keep a minimum of three sponsors (what I have now) at the current rates, that will add up to over $5500 by the time I'm ready to go to college. I like the sound of that (^_^)
Wednesday, February 15, 2006
How Parents Can Save Money With A New Baby
I came across this article titled 32 Ways to Save Money When You Have A Baby over at parents.com. What does saving have to do with investing for my college future? Well, if I can teach my parents to save money, maybe they will take a portion of the savings and donate that to my college fund. I'd much rather it go there than being spent on something that I could get for less.
Here is a summary of the ways you can save according to the article:
At the hospital
1. Say no to add-ons.
2. Don't turn on the TV.
3. Ask for coupons and samples.
4. Take the toiletries.
Budget Breastfeeding
5. Nurse if you possibly can.
6. Borrow a breast pump (**be sure to read comments**)
7. Find out in advance where you can get free breastfeeding advice.
8. Don't rush to buy a breastfeeding wardrobe.
Clothes
9. Don't buy baby clothes far in advance.
10. Scrimp on all-in-ones.
11. Choose unisex shades and styles.
12. Lose the shoes.
13. Buy secondhand special-occasion clothes.
Baby gear
14. Look for furniture and accessories that do double duty.
15. Return unwanted gifts promptly.
16. Don't buy crib pillows.
17. Buy just one or two bottles before your baby is born.
18. Set up a photo Website.
19. When it comes to diapers, buy in bulk.
20. Test-drive a stroller before you buy it.
21. Turn to your local library for classes and games.
22. Keep a baby-care bag in your car.
Health Care
23. Ask your pediatrician for free product samples.
24. Call your pediatrician to talk over a problem before setting up an appointment.
25. Don't buy an ear thermometer. .
Baby Food
26. Hold on to free formula samples and coupons.
27. Sign up for baby-food company newsletters and coupon offers.
28. Make some baby food.
29. Package crunchy toddler snacks in individual airtight containers as soon as you buy them.
Remember to place a little of any money you save into the college savings account!
If you have a newborn, you're probably panicked too. No wonder: Depending on your spending habits and child-care needs, you'll likely shell out $7,000 to $14,600 annually between now and your little one's second birthday. But there's hope. Through trial and error, I learned a lot about raising a daughter on a budget. Now that my second girl is here, I've gotten even savvier. Here are ways you, too, can cut your baby expenses by half—or even more.
Here is a summary of the ways you can save according to the article:
At the hospital
1. Say no to add-ons.
2. Don't turn on the TV.
3. Ask for coupons and samples.
4. Take the toiletries.
Budget Breastfeeding
5. Nurse if you possibly can.
6. Borrow a breast pump (**be sure to read comments**)
7. Find out in advance where you can get free breastfeeding advice.
8. Don't rush to buy a breastfeeding wardrobe.
Clothes
9. Don't buy baby clothes far in advance.
10. Scrimp on all-in-ones.
11. Choose unisex shades and styles.
12. Lose the shoes.
13. Buy secondhand special-occasion clothes.
Baby gear
14. Look for furniture and accessories that do double duty.
15. Return unwanted gifts promptly.
16. Don't buy crib pillows.
17. Buy just one or two bottles before your baby is born.
18. Set up a photo Website.
19. When it comes to diapers, buy in bulk.
20. Test-drive a stroller before you buy it.
21. Turn to your local library for classes and games.
22. Keep a baby-care bag in your car.
Health Care
23. Ask your pediatrician for free product samples.
24. Call your pediatrician to talk over a problem before setting up an appointment.
25. Don't buy an ear thermometer. .
Baby Food
26. Hold on to free formula samples and coupons.
27. Sign up for baby-food company newsletters and coupon offers.
28. Make some baby food.
29. Package crunchy toddler snacks in individual airtight containers as soon as you buy them.
Remember to place a little of any money you save into the college savings account!
Pinecone Survey Link
Hurry - They don't last long. if you're not familiar, Pinecone is one of the few survey sites that pays on a regular basis ($5 per survey), but it is very hard to find their links (you can't sign up on their main page, only through advertised links they change often)
Take the money you earn from their surveys and put it into your college savings. Only one person per family can sign up and if you have a choice, have the man of the house do so (less men in their system means more surveys). Good luck!!
Survey Link
Right side: Top Live Surveys - last one "Pinecone Sign-up Link 1"
Take the money you earn from their surveys and put it into your college savings. Only one person per family can sign up and if you have a choice, have the man of the house do so (less men in their system means more surveys). Good luck!!
Survey Link
Right side: Top Live Surveys - last one "Pinecone Sign-up Link 1"
Tuesday, February 14, 2006
Negotiation College Aid Is An Option
I talked a bit about how prepaid college plans might be an option worth looking at again die to the recent changes in the Deficit Reduction Act of 2005 signed into law last week by President Bush.
I came across an article titled A little help for families trying to pay college expenses which has some good basic information in it and some of the pros and cons with different college saving plans.
Toward the end of the article is a great little piece of advice that I haven't seen often thus far when looking at ways to save money on college costs:
My uncle is big into negotiating and feels it is one of the best ways to keep your hard earned money so he perked up when he came across this little tidbit (and made me look at it twice even though I can't even read yet).
Don't simply accept the college aid that is given, but go back and try to negotiate for more. The worst they can say is "no" and if you can negotiate a better deal, it could mean hundreds to thousands of dollars saved. I'm not remembering a lot yet, but that is one tip I will keep in my mind.
I came across an article titled A little help for families trying to pay college expenses which has some good basic information in it and some of the pros and cons with different college saving plans.
Toward the end of the article is a great little piece of advice that I haven't seen often thus far when looking at ways to save money on college costs:
A further option, Harrington says, is to negotiate a package with college-aid offices that includes tax-free loans and grants. "Too few people know that negotiating is an option," Harrington says.
My uncle is big into negotiating and feels it is one of the best ways to keep your hard earned money so he perked up when he came across this little tidbit (and made me look at it twice even though I can't even read yet).
Don't simply accept the college aid that is given, but go back and try to negotiate for more. The worst they can say is "no" and if you can negotiate a better deal, it could mean hundreds to thousands of dollars saved. I'm not remembering a lot yet, but that is one tip I will keep in my mind.
Saturday, February 11, 2006
The Two Behind The Finances
Here is a photo of my uncle and I in my early days (a few months ago). He's a pretty good guy and we share some memorable moments together including him being the first to almost drop me on my head shortly after the photo was taken. Luckily those years of basketball practice came in handy and the honor of that distinction couldn't officially be given to him.

Me getting in the Xmas spirit. I even let my eyes turn a Xmas red and my hair is coming in a reddish blond. Of course, those have nothing to do with my finances which are not even close to being in the red (^_^)
Tuesday, February 07, 2006
Kids and Saving Money
I came across this article about the positive aspects of helping children to save money:
One of the most important lessons you will teach your children will be how to handle money. If you don't do it proactively, you'll do it by default by not teaching them the skills you wished that your parents and teachers had taught you (pretty deep thinking for a 6 month old, don't you think?)
Don't only save for your children's education and college, but also involve them in it so they learn the importance themselves. I know my parents and uncle will be doing so.
When we give children the opportunity to experience for themselves what it means to save, to have goals for saving, to have their own savings account and to watch the amount of money in their account grow due to their decision (with encouragement and guidance from their parents) to save, they learn what it means to save and about delayed gratification.
One of the most important lessons you will teach your children will be how to handle money. If you don't do it proactively, you'll do it by default by not teaching them the skills you wished that your parents and teachers had taught you (pretty deep thinking for a 6 month old, don't you think?)
Don't only save for your children's education and college, but also involve them in it so they learn the importance themselves. I know my parents and uncle will be doing so.
Saturday, February 04, 2006
Prepaid College Saving Programs Looking Better
I'm trying to learn how to look on the bright side of all situations even when they don't seem to look very good. In that light, here is a little ray of sunshine in the new deficit reduction bill.
The new deficit reduction bill that is waiting for President Bush to sign (he is expected to do so) has a lot of nasty little provisions that will increase the cost of borrowing money for college including cutting $12 billion from student loans and increasing and making fixed (they are currently variable) the current rate of Federal Stafford loans. Among these, however, is one provision that may help those going to college who select to save through prepaid college saving programs.
Prepaid college saving programs allow you to lock in the current tuition rate for a college. There are 12 states that run these programs: Alabama, Florida, Illinois, Maryland, Massachusetts, Michigan, Mississippi, Nevada, Pennsylvania, South Carolina, Tennessee, Virginia and Washington. There is also a consortium of some 250 private colleges (which include the colleges both my parents went to as well as my uncle) that run a prepaid program called Independent 529 college saving program. The program has been popular with parents that want to know the exact rate they will pay for college tuition and are afraid that college tuition will be beyond their means when their children are ready to attend college. There has been a big drawback, however, with how financial aid is calculated with these prepaid programs.
The current problem is that money placed into the prepaid college saving programs is considered the student's money. Under the Federal formula for giving financial aid, this means that the aid available is reduced dollar for dollar with prepaid college savings plans. The new law, however, will treat prepaid college savings plans as they currently treat 529 college savings plans - the money invested in the plan will be considered the parent's money. Since the Federal aid formula for 529 college savings plans states that only 5.64% of the parent's assets should be counted toward college aid, this new designation makes the prepaid college savings plans look a lot more attractive.
There continue to be a number of aspects to the prepaid college saving programs that it's necessary to understand in order to decide if this would be a good plan for your child. Most of the state run programs are restricted to residents living in that state and the tuition is only good toward colleges and universities within that state. Still, as soon as the bill becomes law, it will definitely be worth the time to take a closure look at these programs.
The new deficit reduction bill that is waiting for President Bush to sign (he is expected to do so) has a lot of nasty little provisions that will increase the cost of borrowing money for college including cutting $12 billion from student loans and increasing and making fixed (they are currently variable) the current rate of Federal Stafford loans. Among these, however, is one provision that may help those going to college who select to save through prepaid college saving programs.
Prepaid college saving programs allow you to lock in the current tuition rate for a college. There are 12 states that run these programs: Alabama, Florida, Illinois, Maryland, Massachusetts, Michigan, Mississippi, Nevada, Pennsylvania, South Carolina, Tennessee, Virginia and Washington. There is also a consortium of some 250 private colleges (which include the colleges both my parents went to as well as my uncle) that run a prepaid program called Independent 529 college saving program. The program has been popular with parents that want to know the exact rate they will pay for college tuition and are afraid that college tuition will be beyond their means when their children are ready to attend college. There has been a big drawback, however, with how financial aid is calculated with these prepaid programs.
The current problem is that money placed into the prepaid college saving programs is considered the student's money. Under the Federal formula for giving financial aid, this means that the aid available is reduced dollar for dollar with prepaid college savings plans. The new law, however, will treat prepaid college savings plans as they currently treat 529 college savings plans - the money invested in the plan will be considered the parent's money. Since the Federal aid formula for 529 college savings plans states that only 5.64% of the parent's assets should be counted toward college aid, this new designation makes the prepaid college savings plans look a lot more attractive.
There continue to be a number of aspects to the prepaid college saving programs that it's necessary to understand in order to decide if this would be a good plan for your child. Most of the state run programs are restricted to residents living in that state and the tuition is only good toward colleges and universities within that state. Still, as soon as the bill becomes law, it will definitely be worth the time to take a closure look at these programs.
Friday, February 03, 2006
Shop Around For Your College
I am learning in my early age that one way to save money on college is to shop around. It's similar to shopping for brand named merchandise. If I have my heart set on a single college it's likely to cost me a lot more money. If I have several in mind that I like, then I can also take into account any aid they are willing to give to lower the cost. This seems to be a growing trend as this article shows
Although I plan to have saved up enough to attend any college I want, I also plan to shop smart. I hope I can find a number of good colleges I want to attend and then choose on a variety of factors to go to the one that best suits me. Starting to save early, however, will give me a lot more choices so that money doesn't have to be the only factor I consider.
Lindsey Mackney's choice of colleges came down to two very different places: Boston University, with its urban appeal and lively youth culture, or Allegheny College, a small, friendly liberal arts institution here in the rolling hills of northwest Pennsylvania.
In the end, Mackney said, the decision was simple. Boston, where tuition is $31,530 a year, offered her no financial aid, while Allegheny awarded her a $50,000 merit scholarship, or $12,500 a year. That's nearly a 50 percent discount of Allegheny's $26,650 tuition.
Squeezed on one side by state universities, whose tuition is a tiny fraction of what private colleges charge, and on the other by elite private institutions like Yale, Princeton or Amherst, private liberal arts colleges like Allegheny are routinely offering merit aid to students these days. Such scholarships are particularly pervasive in the Midwest, where many liberal arts colleges award them to as much as half or three-quarters of their students.
The grants are not based on the traditional rationale of a family's financial need, but on academic achievement and the desire of colleges that are not among the nation's most prestigious to recruit high-achieving students. Sometimes, too, less-elite colleges award merit aid simply to fill their freshman classes.
Although I plan to have saved up enough to attend any college I want, I also plan to shop smart. I hope I can find a number of good colleges I want to attend and then choose on a variety of factors to go to the one that best suits me. Starting to save early, however, will give me a lot more choices so that money doesn't have to be the only factor I consider.
Thursday, February 02, 2006
January Net Worth
January was a busy month. I've started to learn how to crawl although I'm much better at going backward than forward. That's fine with me as I like doing things a bit differently. How many other 7 month olds do you know blogging and saving money? (^_^)
January didn't turn out to be a wonderful month for increasing my net worth. The one bright spot was Upromise that unexpectedly added $25 this past month. The only other real income I had was getting another sponsor that paid for 6 months in advance. Other advertising was not too good this month mainly because I didn't post enough (hint, hint uncle) which meant I didn't have as many visitors as I have in the past. With only an increase of $81.70 this month I came in well below the $3000 mark I had set as a goal. Still, my net worth increased 2.79% and I'm quickly closing in on the $3000 mark and I should be able to surpass it this month.
With my net worth currently standing at $2926.55 I'll shoot again for a 5% increase in February or $146.33 for a total of $3072.88. My uncle has assured me that he'll spend a bit more time working on my net worth this month.
In looking at my asset allocation, I have way too much money in cash not earning anything. I'm waiting to see what the I-bond does at the next switch. My parents and uncle will also be getting together in May when they can make some decisions together on the best place to put the extra money.
January didn't turn out to be a wonderful month for increasing my net worth. The one bright spot was Upromise that unexpectedly added $25 this past month. The only other real income I had was getting another sponsor that paid for 6 months in advance. Other advertising was not too good this month mainly because I didn't post enough (hint, hint uncle) which meant I didn't have as many visitors as I have in the past. With only an increase of $81.70 this month I came in well below the $3000 mark I had set as a goal. Still, my net worth increased 2.79% and I'm quickly closing in on the $3000 mark and I should be able to surpass it this month.
With my net worth currently standing at $2926.55 I'll shoot again for a 5% increase in February or $146.33 for a total of $3072.88. My uncle has assured me that he'll spend a bit more time working on my net worth this month.
In looking at my asset allocation, I have way too much money in cash not earning anything. I'm waiting to see what the I-bond does at the next switch. My parents and uncle will also be getting together in May when they can make some decisions together on the best place to put the extra money.
Thursday, January 26, 2006
College Loans Eating Up Salaries
I came across this interesting article about how many people graduating college are doing so in such debt that the debt is eating up a significant portion of their salaries. It's just another reason to start early and save. if I can come out of college debt free I feel that I will be in a wonderful financail position. From the article:
Entire Article
John Donald and Teresa Bujacich, both health care professionals, don't consider themselves poor, and they wouldn't meet anyone's objective measure of being poor.
Yet they share many of the same challenges as other working poor in the Seattle area. They watchdog their budget, juggle bill payments and live month-to-month. There is no money to save for retirement. No emergency fund. They've made a lifestyle choice not to buy cell phones and cable TV, but even if they wanted to, they could barely afford them. Mini-mansions have popped up like mushrooms in the area surrounding their practice, but they are raising their baby in a modest one-bedroom condominium in Bothell, a 30-minute drive from their work.
The reason? Student-loan debt.
Between the two, Donald, an acupuncturist, and Bujacich, who is both a naturopath and acupuncturist, have 16 years of higher education and nearly $350,000 in student loans, a massive liability that costs them $1,700 a month in loan payments.
Entire Article
Sunday, January 22, 2006
Busy Week
There wasn't anything posted this past week because my uncle was extremely busy re-launching his Financial Challenges. I keep telling him that he needs to learn to take afternoon naps like me. They are so wonderful and grown-ups underestimate their value. I'll continue to try and get through to him on this.
There haven't been any major developments in my finances, but he is going to look for some new investment antiques for me this week. I would have my fingers crossed if I could (still working on that hand - eye coordination thing although I do have one mean grip!) and hopefully i can add a bit more to my net worth before the end of the month.
There haven't been any major developments in my finances, but he is going to look for some new investment antiques for me this week. I would have my fingers crossed if I could (still working on that hand - eye coordination thing although I do have one mean grip!) and hopefully i can add a bit more to my net worth before the end of the month.
Sunday, January 15, 2006
Eddie Bauer $25 Gift Card
As I have noted before, one of the best ways to save money for college is to take advantage of free money when it's available. Eddie Bauer is giving a $25 electronic gift card (The Eddie Bauer e-gift card can be redeemed in our stores, catalog and online at eddiebauer.com) for feedback about their summer catalog (hurry, these usually don't last long!)
http://eddiebauer.com/feedback
If you regularly shop at Eddie Bauer, then take $25 and put it into you kid's college fund. If you don't, you have a nice gift for yourself for taking a survey!
http://eddiebauer.com/feedback
If you regularly shop at Eddie Bauer, then take $25 and put it into you kid's college fund. If you don't, you have a nice gift for yourself for taking a survey!
Saturday, January 14, 2006
$5000 High School Senior Ethics Essay Contest
When I get older (and learn how to write), I'm going to enter a lot of different essay contests for scholarship money. The way I see it, the more I can get through essays and contests, the more I can save toward retirement (boy, doesn't that sound funny - a six month old talking about retirement) or other financial goals. There are a lot of essay contests out there and I will post any that I happen to come across. Here is one from Junior Achievement:
High School Seniors: Enter the "Excellence through Ethics" Essay Contest for the chance to win a $5,000 college scholarship!
Junior Achievement teaches students how to be successful in our free enterprise system. The students understand business, and they value ethics. JA defines ethics as rules or standards, for right/good behavior or actions.
Entries will be accepted until February 3
Contest Rules
This is the ethics question for the essay:
Lawn Care Service
Jessica, 17, has a summer-time lawn care business. One of Jessica’s customers is a neighbor, the Lee family. Jessica has mowed the lawn for Mr. and Mrs. Lee every week during the summer. Jessica is paid $20.00 each time she mows the lawn. Mr. and Mrs. Lee, who are unable to care for their yard themselves, frequently ask Jessica to do other yard work in addition to mowing the lawn. Jessica often pulls weeds, plants flowers, rakes leaves, and spreads mulch and pine straw. Mr. and Mrs. Lee have not offered extra wages for the additional work, and Jessica has been too shy to ask. Jessica’s other customers pay her additional wages for extra yard work beyond mowing.
Jessica is saving all of her money from her lawn mowing business for college. She is responsible for paying her tuition and all expenses and would like to make as much as possible this summer. One day, Jessica worked two extra hours pulling weeds at the home of Mr. and Mrs. Lee after mowing the lawn. While checking her day’s payments at home that evening, Jessica noticed that an extra $100 bill was tucked inside the regular $20.00 bill from Mr. and Mrs. Lee. Jessica knows she has worked enough during the past summer to deserve the extra money, but she does not know if the Lees meant to give her such a large payment. Jessica wonders what she should do.
Essay Question: Jessica is faced with an ethical business decision. In 500 words or less, describe what Jessica should do. Be sure to explore the potential consequences of her response and why you think it is the most appropriate solution to the situation. Consider ethical behavior and decision-making as the foundation of your argument.
Thanks to Chree's World for pointing this contest out.
High School Seniors: Enter the "Excellence through Ethics" Essay Contest for the chance to win a $5,000 college scholarship!
Junior Achievement teaches students how to be successful in our free enterprise system. The students understand business, and they value ethics. JA defines ethics as rules or standards, for right/good behavior or actions.
Entries will be accepted until February 3
Contest Rules
This is the ethics question for the essay:
Lawn Care Service
Jessica, 17, has a summer-time lawn care business. One of Jessica’s customers is a neighbor, the Lee family. Jessica has mowed the lawn for Mr. and Mrs. Lee every week during the summer. Jessica is paid $20.00 each time she mows the lawn. Mr. and Mrs. Lee, who are unable to care for their yard themselves, frequently ask Jessica to do other yard work in addition to mowing the lawn. Jessica often pulls weeds, plants flowers, rakes leaves, and spreads mulch and pine straw. Mr. and Mrs. Lee have not offered extra wages for the additional work, and Jessica has been too shy to ask. Jessica’s other customers pay her additional wages for extra yard work beyond mowing.
Jessica is saving all of her money from her lawn mowing business for college. She is responsible for paying her tuition and all expenses and would like to make as much as possible this summer. One day, Jessica worked two extra hours pulling weeds at the home of Mr. and Mrs. Lee after mowing the lawn. While checking her day’s payments at home that evening, Jessica noticed that an extra $100 bill was tucked inside the regular $20.00 bill from Mr. and Mrs. Lee. Jessica knows she has worked enough during the past summer to deserve the extra money, but she does not know if the Lees meant to give her such a large payment. Jessica wonders what she should do.
Essay Question: Jessica is faced with an ethical business decision. In 500 words or less, describe what Jessica should do. Be sure to explore the potential consequences of her response and why you think it is the most appropriate solution to the situation. Consider ethical behavior and decision-making as the foundation of your argument.
Thanks to Chree's World for pointing this contest out.
Teaching Children About Money
One of the important activities that parents need to do is teach their children about money because schools simply don't (at least that is what I have heard. It's a little difficult to go to school when you haven't learned to talk, crawl or dress yourself). Here is an article that discusses some of the activities and games that you can use to help teach your child about money: Tips & Toys for Teaching Kids Financial Smarts
Tuesday, January 10, 2006
The Toddler's Diet
This isn't financial, but it's good to know that I won't need to worry about my weight in the toddler years. I also wanted to pass a message along to mom and dad about what fun they can expect in the years to come:
The Toddler's Diet
DAY ONE
• Breakfast - One scrambled egg, one piece of toast with grape jelly. Eat 2 bites of egg, using your fingers; dump the rest on the floor. Take 1 bite of toast, then smear the jelly over your face and clothes.
• Lunch - Four crayons (any color), a handful of potato chips, and a glass of milk (3 sips only, then spill the rest).
• Dinner - A dry stick, two pennies and a nickel, 4 sips of stale soda.
• Bedtime Snack - Toast piece of bread and toss it on the kitchen floor.
DAY TWO
• Breakfast - Pick up stale toast from kitchen floor and eat it. Drink half bottle of vegetable dye.
• Lunch - Half a tube of "Pulsating Pink" lipstick. One ice cube, if desired.
• Afternoon Snack - Lick an all-day sucker until sticky, take outside, drop In dirt. Retrieve and continue slurping until it is clean again. Then bring inside and drop on the rug.
• Dinner - A rock or an uncooked bean, which should be thrust up your left nostril. Pour iced tea over mashed potatoes; eat with a spoon.
DAY THREE
• Breakfast - Two pancakes with plenty of syrup, eat with fingers, rub in hair. Glass of milk: drink half, stuff pancakes in glass. After breakfast, pick up yesterday's sucker from rug, lick off fuzz, and put it on the cushion of your best chair.
• Lunch - Three matches, peanut butter and jelly sandwich. Spit several bites onto the floor. Pour glass of milk on table and slurp up.
• Dinner - Dish of ice cream, handful of potato chips, some coffee.
FINAL DAY
• Breakfast - A quarter-tube of toothpaste (any flavor), bit of soap, an olive. Pour a glass of milk over bowl of corn flakes, add a half-cup of sugar. Once cereal is soggy, drink milk and feed cereal to dog.
• Lunch - Eat crumbs off kitchen floor and dining room carpet. Find that sucker and finish eating it.
• Dinner - A glass of spaghetti and chocolate milk. Leave meatball on plate. Stick of mascara for dessert!
and some added dieting techniques:
1. Refuse to eat unless you are sitting on someone's lap. Drop most of food on your parents' clothes.
2. Refuse to wear bib unless all others present also wear bibs.
3. Eat pretzels for breakfast, lunch and dinner. Refuse all other food.
4. Demand food that you've only tasted once long ago that nobody knew you'd remember the name of, and which is not on in the house.
5. Eat very little breakfast, almost no lunch, and no dinner. Go to sleep. Wake up at 1 AM and demand hot dogs with ketchup.
6. When your Papa is too sleepy to protest, convince him to let you eat graham crackers in bed. Make lots of crumbs. Demand for weeks afterwards to be given graham crackers in bed. Howl loudly when denied.
7. When served a bowl of soup, take a fancy to one particular ingredient of the soup, like the noodles. Force your parents to choose between watching you go hungry, or picking out all the noodles (from your bowl and their own bowls) to give to you.
8. Eat a large, well balanced meal. Then, while playing, throw up your entire meal on the rug. Appear to be fine immediately afterwards.
9. Reject an entire box of animal cookies because the lions have all been eaten. Also, reject all the ones that are broken.
10. Choose a food-of-the-week. Eat nothing but that food for an entire week. If that food is denied, eat nothing. (examples: pizza, applesauce, pretzels, oranges).
Source: Saving Advice Forums
The Toddler's Diet
DAY ONE
• Breakfast - One scrambled egg, one piece of toast with grape jelly. Eat 2 bites of egg, using your fingers; dump the rest on the floor. Take 1 bite of toast, then smear the jelly over your face and clothes.
• Lunch - Four crayons (any color), a handful of potato chips, and a glass of milk (3 sips only, then spill the rest).
• Dinner - A dry stick, two pennies and a nickel, 4 sips of stale soda.
• Bedtime Snack - Toast piece of bread and toss it on the kitchen floor.
DAY TWO
• Breakfast - Pick up stale toast from kitchen floor and eat it. Drink half bottle of vegetable dye.
• Lunch - Half a tube of "Pulsating Pink" lipstick. One ice cube, if desired.
• Afternoon Snack - Lick an all-day sucker until sticky, take outside, drop In dirt. Retrieve and continue slurping until it is clean again. Then bring inside and drop on the rug.
• Dinner - A rock or an uncooked bean, which should be thrust up your left nostril. Pour iced tea over mashed potatoes; eat with a spoon.
DAY THREE
• Breakfast - Two pancakes with plenty of syrup, eat with fingers, rub in hair. Glass of milk: drink half, stuff pancakes in glass. After breakfast, pick up yesterday's sucker from rug, lick off fuzz, and put it on the cushion of your best chair.
• Lunch - Three matches, peanut butter and jelly sandwich. Spit several bites onto the floor. Pour glass of milk on table and slurp up.
• Dinner - Dish of ice cream, handful of potato chips, some coffee.
FINAL DAY
• Breakfast - A quarter-tube of toothpaste (any flavor), bit of soap, an olive. Pour a glass of milk over bowl of corn flakes, add a half-cup of sugar. Once cereal is soggy, drink milk and feed cereal to dog.
• Lunch - Eat crumbs off kitchen floor and dining room carpet. Find that sucker and finish eating it.
• Dinner - A glass of spaghetti and chocolate milk. Leave meatball on plate. Stick of mascara for dessert!
and some added dieting techniques:
1. Refuse to eat unless you are sitting on someone's lap. Drop most of food on your parents' clothes.
2. Refuse to wear bib unless all others present also wear bibs.
3. Eat pretzels for breakfast, lunch and dinner. Refuse all other food.
4. Demand food that you've only tasted once long ago that nobody knew you'd remember the name of, and which is not on in the house.
5. Eat very little breakfast, almost no lunch, and no dinner. Go to sleep. Wake up at 1 AM and demand hot dogs with ketchup.
6. When your Papa is too sleepy to protest, convince him to let you eat graham crackers in bed. Make lots of crumbs. Demand for weeks afterwards to be given graham crackers in bed. Howl loudly when denied.
7. When served a bowl of soup, take a fancy to one particular ingredient of the soup, like the noodles. Force your parents to choose between watching you go hungry, or picking out all the noodles (from your bowl and their own bowls) to give to you.
8. Eat a large, well balanced meal. Then, while playing, throw up your entire meal on the rug. Appear to be fine immediately afterwards.
9. Reject an entire box of animal cookies because the lions have all been eaten. Also, reject all the ones that are broken.
10. Choose a food-of-the-week. Eat nothing but that food for an entire week. If that food is denied, eat nothing. (examples: pizza, applesauce, pretzels, oranges).
Source: Saving Advice Forums
Monday, January 09, 2006
Doing Well - Monthly Allowance
According to ING, kids age 5 - 12 receive the following amount in monthly allowance:
$5 or less: 13%
$6 - $10: 23%
$11 - $20: 39%
$21 or more: 24%
Looking at my current savings, I figured out the following. If I average $20 a month for my allowance, then I have already saved over 11 years worth! ($2800 divided by $20 = 140 months divided by 12 months = 11.66 years).
That also has me thinking that if I can save a portion of my allowance when I get older, I can add even more to my savings!
$5 or less: 13%
$6 - $10: 23%
$11 - $20: 39%
$21 or more: 24%
Looking at my current savings, I figured out the following. If I average $20 a month for my allowance, then I have already saved over 11 years worth! ($2800 divided by $20 = 140 months divided by 12 months = 11.66 years).
That also has me thinking that if I can save a portion of my allowance when I get older, I can add even more to my savings!
AAA Travel High School Challenge Scholarship
It's still years away until I can compete in something like this, but since my uncle loves to travel and I hope to take some trips with him, I'm hoping that scholarships like this are still around when I'm ready for college. The deadline is January 17, so go to register now
The AAA Travel High School Challenge is being repeated in 2006! More than just a geography contest, this scholarship program tests students' travel literacy by focusing on tourism destinations. It encourages youngsters to study geography and to consider careers in the travel and tourism industry. Designed by travel industry educator Dr. Marc Mancini and sponsored by AAA preferred partners, the Challenge is a three stage competition with over $100,000 in college scholarship funds up for grabs. Ninth through 12th grade public, private and home-schooled students throughout the United States can put their travel knowledge to the test for great prizes and a chance to compete in the national finals in Orlando, FL.
The AAA Travel High School Challenge is being repeated in 2006! More than just a geography contest, this scholarship program tests students' travel literacy by focusing on tourism destinations. It encourages youngsters to study geography and to consider careers in the travel and tourism industry. Designed by travel industry educator Dr. Marc Mancini and sponsored by AAA preferred partners, the Challenge is a three stage competition with over $100,000 in college scholarship funds up for grabs. Ninth through 12th grade public, private and home-schooled students throughout the United States can put their travel knowledge to the test for great prizes and a chance to compete in the national finals in Orlando, FL.
Saturday, January 07, 2006
$5 American Express Gift Card
One of the best ways to add little amounts to a college fund is to get free money whenever you can.
American Express through the Women's Business Initiative is offering a $5 Amex gift card for a short survey. Get the gift card and place $5 into your college savings account!
$5 American Express Gift Card
American Express through the Women's Business Initiative is offering a $5 Amex gift card for a short survey. Get the gift card and place $5 into your college savings account!
$5 American Express Gift Card
Friday, January 06, 2006
New Sponsor!
I have a new sponsor and he even made a long term commitment! He decided to sponsor me for 6 months and after a small discount for the long term commitment and taking out fees, I was able to add $46.27 to my net worth. The best part is that I can count this as earned income and earmark it for the Roth IRA I want to open.
I hope that I can find some other sponsors in the months to come as that will certainly help my overall net worth and savings for college.
I hope that I can find some other sponsors in the months to come as that will certainly help my overall net worth and savings for college.
Happy 6 Months To Me!
Can you believe it? I'm half a year old today and have been writing this more than half my life! I hope the next 6 months are as much fun as the first six.
Sunday, January 01, 2006
The Costs of College
I hope that I can make a wise decision as to where I get my college education without having to have money come in as a factor, but the reality for most students is that money does play a role when deciding where to go to college. Here is a little piece through the eyes of four freshman college students about paying for college:
I think this will be a fundamental question I will have to deal with. When does cost exceed the value of the education given? While I hope to save enough to attend any college I want, I would also like to leave college with some savings still intact. I will have to think about this more later...right now it's time for my nap
This combination of more selective admissions and higher tuition prices can cause much anxiety for high school students and their families. For many of those who are accepted by a college or university, alternate ways to pay are out there. Although in years past, a summer job, a little help from the parents, and maybe a small loan have been enough to cover costs, that is no longer the case.
I think this will be a fundamental question I will have to deal with. When does cost exceed the value of the education given? While I hope to save enough to attend any college I want, I would also like to leave college with some savings still intact. I will have to think about this more later...right now it's time for my nap
My 2006 Financial Goals
I need to make some goals for myself for 2006. Beside the basic ones like learning to turn over well, how to say "mom" and "dad" and all those other good things, I also want to set some financial goals for this year. Since it is still early in my career, I'm not sure how well I will do in meeting these, but I think it's important to have goals to shoot for to help keep you focused (let me say that I'm now much better on focusing than I was a few months ago) on what you want to achieve. These are my 3 financial goals for 2006:
I'd like to have a net worth of $7500 by the end of the year.
I'd like for this site to be generating $50 a month by the end of the year.
I'd like to have earned enough money on my own to open a Roth IRA and begin investing in it.
I'd like to have a net worth of $7500 by the end of the year.
I'd like for this site to be generating $50 a month by the end of the year.
I'd like to have earned enough money on my own to open a Roth IRA and begin investing in it.
January Goals & December Goals Review
December was a good month with the help of a couple of gifts. I didn't meet all my goals, but I did surpass a few of them that I set.
My goal for my net worth at the end of December was to increase it to $2588.29 which I surpassed by over $250. I still like the 5% increase in my net worth per month since I don't have any expenses (thanks mom and dad). That would put my goal to increase my net worth by $142.24 or a total of $2987.09, so lets shoot for an even $3,000.
I haven't been doing well on getting my articles into carnivals to show off the site to new people. I really need to do a better job of that. I do have a post that should be in 2 different carnivals this Monday and I hope to get into at least 3 more after that which would make a total of 5 for the month.
I finally got ahead on my link trades and ended up with 17 while the goal was 15. I'll shoot for 20 ending this month. I failed to get another sponsor for the site and that will be one of my top priorities this month.
I did much better on the auctions this month getting all 10 up and selling 9 out of the 10. Now the problem is that I don't have any investments there and a pile of cash. I hope to spend at least $500 on acquiring new antique investments. I also have too much cash on hand so I need to stick that in an account where I can earn some interest on it.
I hope to have a good year with my finances and hope that all of you enjoy the ride along with me.
My goal for my net worth at the end of December was to increase it to $2588.29 which I surpassed by over $250. I still like the 5% increase in my net worth per month since I don't have any expenses (thanks mom and dad). That would put my goal to increase my net worth by $142.24 or a total of $2987.09, so lets shoot for an even $3,000.
I haven't been doing well on getting my articles into carnivals to show off the site to new people. I really need to do a better job of that. I do have a post that should be in 2 different carnivals this Monday and I hope to get into at least 3 more after that which would make a total of 5 for the month.
I finally got ahead on my link trades and ended up with 17 while the goal was 15. I'll shoot for 20 ending this month. I failed to get another sponsor for the site and that will be one of my top priorities this month.
I did much better on the auctions this month getting all 10 up and selling 9 out of the 10. Now the problem is that I don't have any investments there and a pile of cash. I hope to spend at least $500 on acquiring new antique investments. I also have too much cash on hand so I need to stick that in an account where I can earn some interest on it.
I hope to have a good year with my finances and hope that all of you enjoy the ride along with me.
Subscribe to:
Posts (Atom)